Brazil Endoscopy Devices Market 2026 – 2035
Report Overview
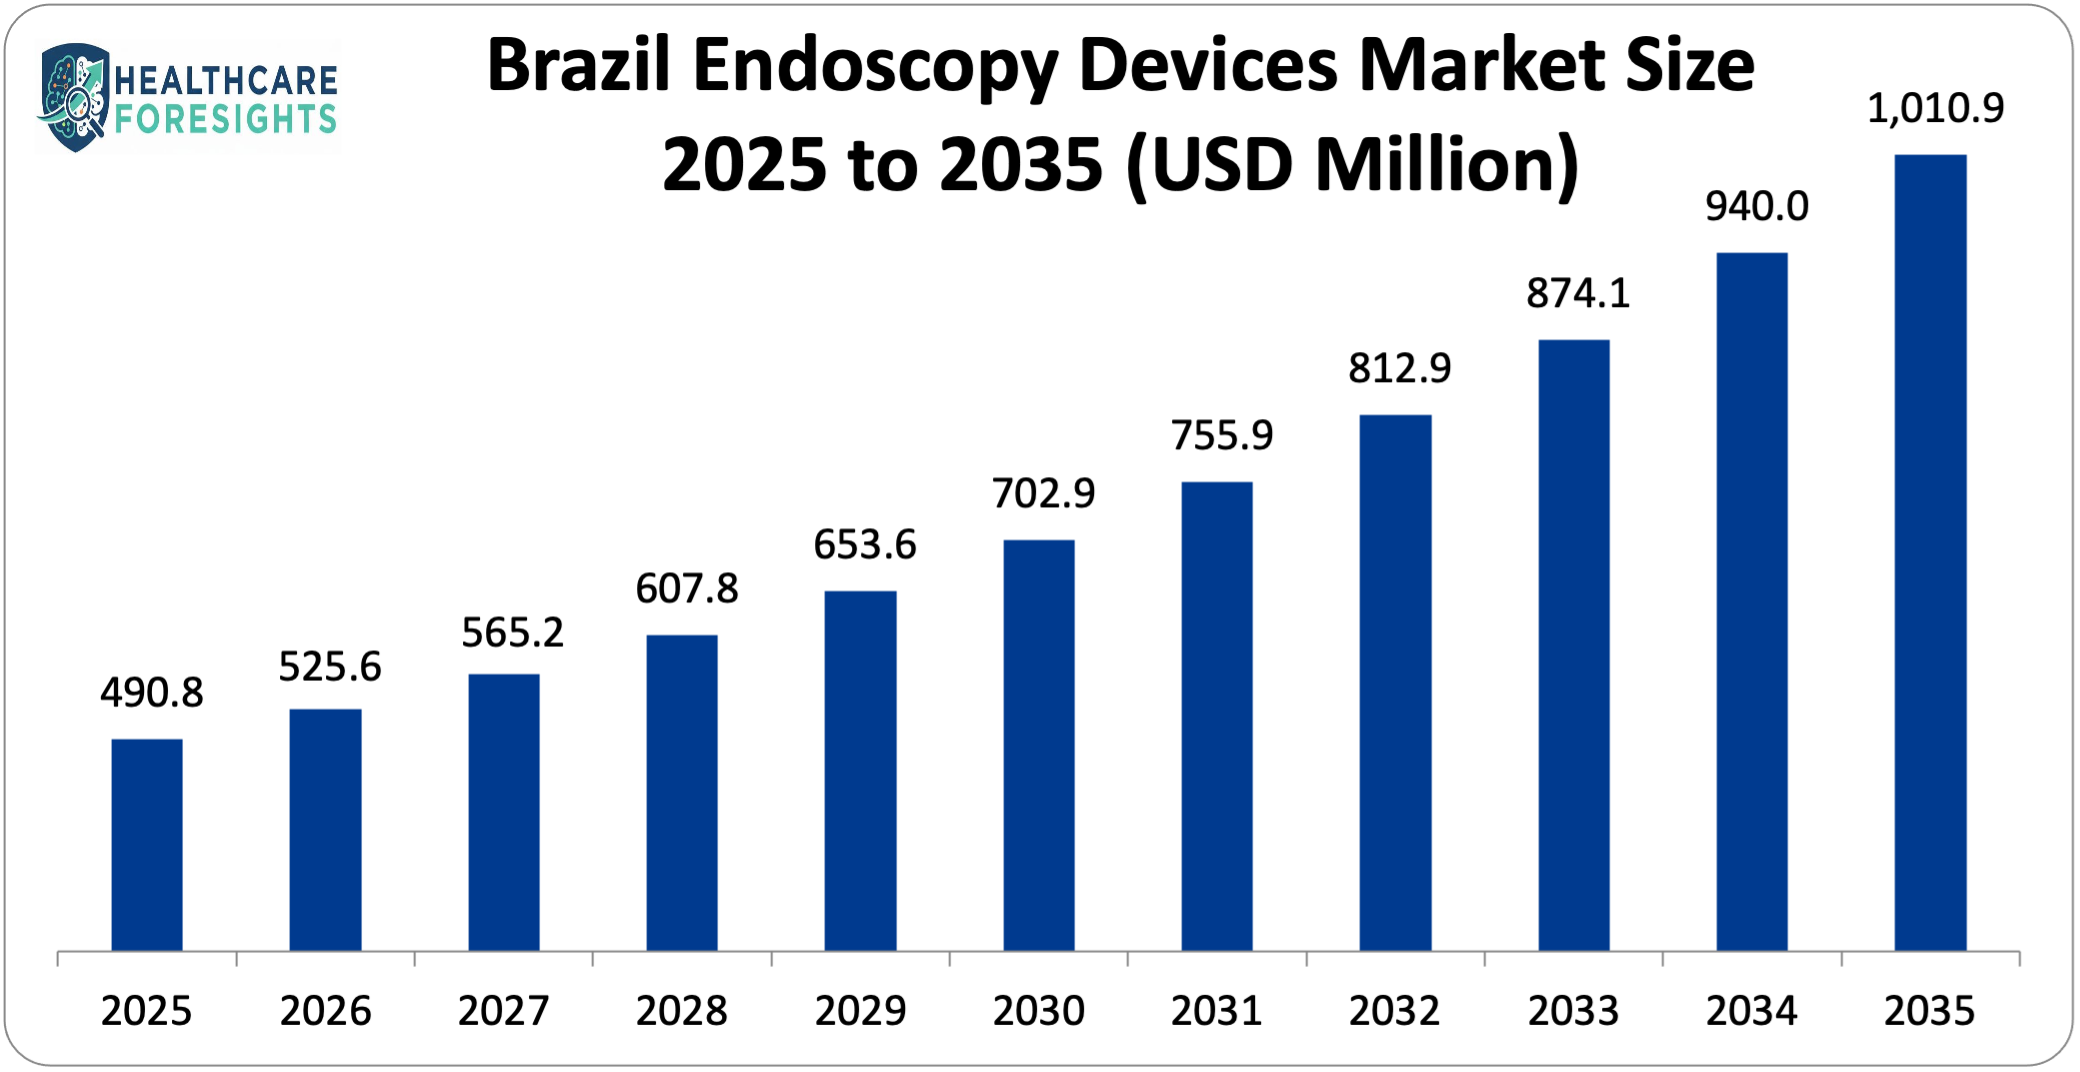
Brazil's endoscopy devices market is projected to be USD 526.6 million in the year 2026, USD 1010.9 million in the year 2035 and at a projected CAGR of 7.8% between the years 2026 and 2035.
The associated rise of gastrointestinal disorders and the mounting demand to undergo surgery in a minimally invasive procedure and the growing healthcare spending in the entire country are the key factors that have caused this growth. Research on health awareness, the growth of diagnostic and surgical centers, and the extensive implementation of modern imaging and endoscopy technologies are also contributing to the growth of the market.
Market Highlight
By product type, Endoscopes dominated the market in 2025, driven by rising minimally invasive procedure volumes and screening demand.
By end user, the hospital held the largest market share, fueled by advanced infrastructure and higher complex procedure capacity.
By application, Gastrointestinal (GI) Endoscopy led total sales, supported by increasing colorectal screenings and digestive disease prevalence.
Significant Growth Factors
Increased Incidence of Gastrointestinal and Chronic Diseases: The growing prevalence of gastrointestinal (GI) diseases including colorectal cancer, gastritis, ulcers and inflammatory bowel diseases is an important catalyst of endoscopy devices in Brazil. There is rising demand for diagnostic and therapeutic endoscopic procedures as these diseases are on the rise. Endoscopies are needed to directly look inside the body and to diagnose early and treat with the least invasive approach, and they are becoming more popular than the conventional open surgery. Moreover, increasing age, more likely to result in chronic digestive and urological diseases, enhances the necessity of regular screenings and endoscopic procedures. The increased use of endoscopy devices in both hospitals and clinics throughout the country is being fuelled by health awareness programs and government screening programs, particularly of colorectal cancer. Colorectal cancer ranks as one of the most prevalent cancers in Brazil, and approximately 704,000 total cancer cases will be experienced between 2023 and 2025, which will overburden the volume of diagnostic endoscopy. The GI segment is a major market segment within endoscopy devices.
Increasing Use of Minimally Invasive Procedures: Minimally invasive surgeries, such as endoscopic diagnostics and treatment, are becoming highly popular with both clinicians and patients in Brazil because of their benefits: smaller incisions, less post-operative pain, shorter stays, and fewer complications. Endoscopy equipment such as flexible and disposable endoscopes allows the improvement of visualization and targeted treatment, which is in line with the global trends in healthcare, where patient comfort and efficiency are essential. The adoption of state-of-the-art endoscopy systems is a growing trend in hospitals and ambulatory surgical centers because they minimise procedure time and enhance throughput. This is part of general tendencies in the field of surgery where the country is updating its health facilities and surgery capacity.
Growth of Healthcare Infrastructure and Access: Brazil is making more investments in hospitals, ambulatory surgery centers and specialty clinics, which is opening more access to endoscopy services. Modern diagnostic and surgical facilities are available in new and improved ones in the urban and semi-urban areas, making it easy to adopt advanced endoscopes. Increased infrastructure expansion also enables increased volumes of procedures, wait times and patient throughput. There is also the growth of outpatient surgery facilities, which offer increased local access and make the facilities more convenient to patients as well as more widely adopted on the market. More than 3 of the 100 Brazilian medium-sized cities have renovated or newly created endoscopy capable clinics over the last five years.
What are the single Biggest Developments Reshaping the Brazil endoscopy devices market Today?
High Price of Advanced Endoscopy Equipment: HD, 3D and robot-assisted endoscopes are expensive systems to invest in. Public hospitals that have limited budgets and have smaller clinics might delay purchase and limit adoption. On top of the acquisition, there are operational expenses like maintenance, consumables and software upgrades, which contribute to the financial load. With the high upfront cost, it restricts access in the low-income or rural areas. The high-definition endoscopy system may be 3-5 times more expensive than a normal analog system to initially purchase, thus restricting its adoption in small facilities.
Low Availability of Trained Endoscopy Professionals: There is a shortage of trained endoscopists and support technicians, particularly in the non-urban areas of Brazil. Complex endoscopic interventions need expert skills, and training needs might be inadequate to address demand. This reduces the number of procedures that a hospital can carry out and retards the use of advanced equipment, especially robot assisted and disposable systems. Most of the regional hospitals have fewer than 2 trained endoscopists to cater to a population of over 200,000 individuals, which poses a bottleneck during the procedure.
High Cleaning, Sterilizing, and Maintenance Costs: Reusable endoscopes require special staff and equipment to meet the requirements of cleaning, sterilizing, and maintaining the equipment to prevent infections. The cost of ownership is enhanced by operational complexity and recurrent costs. Smaller clinics can have issues with quality standards, restricting the number of procedures and device implementation. Reusable endoscopes have operational costs that can take up a figure of 20-30 percent of the total annual expenditure of mid-sized clinics.
Regulatory and Compliance Hurdles: ANVISA medical device approval regulations involve stringent approval procedures. Manufacturers are expected to meet documentation, safety, and performance requirements, which may slow down availability of products. The regulatory obstacles have the ability to restrict the use of new technologies or foreign devices and raise expenses because of compliance measures, slowing down the overall development of the market. The time of approval of the devices may take 6 to 12 months, based on complexity, as it impacts the procurement schedule of the hospital.
Category Wise Insights
By Product Type
Why are Endoscopes the Market Leaders?
Endoscopes dominate the Brazilian endoscopy devices market since this product line is the centerpiece of the tools needed to carry out the diagnostic and treatment procedures in various specialties such as gastroenterology, urology, gynecology, pulmonology, and orthopedics. And each endoscopic practice involves having a scope, and this segment is basic to the market. The growing number of minimally invasive surgeries and diagnostic screenings is what is directly causing the demand for rigid, flexible, and disposable endoscopes. Also, the growing inclination towards early disease identification and outpatient treatment has amplified the rate of procedures within hospitals and outpatient centers. The sustained innovation of high-definition images, single-use scopes, and infection-prevention solutions enhances the competitiveness of the segment by further dominating the revenues of this industry in Brazil.
Why are Endoscopy Visualization Systems Fastest-Growing Segment?
The visualization systems of endoscopy are rapidly growing because of the growing needs of high-definition (HD) and 3D visualization methods of endoscopy which contribute to the higher accuracy of the diagnosis and a higher degree of precision during the procedure. Current hospitals in Brazil are abandoning the standard-definition systems to upgrade to HD and modern visualization systems in order to enhance clinical outcomes. Better visualization in images allows doctors to better see smaller lesions and abnormalities and minimize the risk of misdiagnosis. Moreover, medical practitioners are also investing in state-of-the-art systems to be competitive and be able to appeal to patients who want up-to-date treatment. Visualization systems are essential in precision-based interventions as the procedural complexity increases hence this segment is one of the fastest growing product segments in the market.
By Application
Why is Gastrointestinal (GI) Endoscopy the Largest Application Segment?
It is dominated by gastrointestinal endoscopy because of the large number of patients with digestive disorders, colorectal cancer screening, gastrointestinal problems, and liver complications. Repeat colonoscopy and upper GI are both being highly advised for adult patients over a specific age, which has led to steady volumes of procedures. The use of preventive screening awareness and early diagnosis programs also increases GI procedure frequency. With the increase in the number of lifestyle-related diseases, the demand for GI diagnostics and therapeutic interventions is on the increase, and therefore this is the biggest application area in Brazil.
Why is the Laparoscopy Segment Growing Rapidly?
The laparoscopy is developed rapidly because it is a minimally invasive procedure and has wide usage in general surgery, bariatrics and abdominal surgery. Shorter recovery periods, fewer hospitalizations, and the minimization of comorbidity motivate both the surgeons and patients to adopt the laparoscopic surgeries. To ensure continued growth in the segment, there is increased use of the minimally invasive surgical methods in public and private hospitals.
By End-use
What is the Hospital being the End-use?
Hospitals prevail since they carry out most of the complicated and high volume endoscopic operations. They have well developed infrastructure, professional specialists and financial ability to invest in high definition systems and working devices. The tertiary hospitals deal with complex cases that demand a higher order of visualization and intervention equipment leading to increased procurement rates of the equipment. In Brazil, both diagnostic and therapeutic endoscopy procedures are concentrated in the public and private hospitals.
Why are Ambulatory Surgery Centers the Fastest-Growing end use?
The number of ambulatory surgery centers and clinics is growing because of the growing popularity of outpatient and same-day surgical procedures. Minimally invasive endoscopy would fit this model and save the hospitalization expenses, as well as enhance patient convenience. Increased amount of private healthcare institutions and increasing demand of cost-effective treatments are some of the factors that make this segment grow faster.
Report Scope
Feature of the Report | Details |
Market Size in 2026 | USD 526.6 million |
Projected Market Size in 2035 | USD 1010.9 million |
Market Size in 2025 | USD 490.8 million |
CAGR Growth Rate | 7.8% CAGR |
Base Year | 2025 |
Forecast Period | 2026-2035 |
Key Segment | By Product, Application, End‑use and Region |
Report Coverage | Revenue Estimation and Forecast, Company Profile, Competitive Landscape, Growth Factors and Recent Trends |
Buying Options | Request tailored purchasing options to fulfil your requirements for research. |
Key Developments
The Brazil endoscopy devices market is experiencing good product innovation and portfolio development, with the major medical device manufacturers concentrating on improving precision in imaging, efficiency in the performance of each procedure, infection control, and minimally invasive properties. The companies are also unveiling new high-definition (HD) and 3D visualization solutions, single-use endoscopes, robot-assisted systems, and integrated towers to support the changing requirements of hospitals and ambulatory surgery centers.
In October 2022, Allurion was given a green light to roll out its gastric balloon in Brazil, which is a major move towards international presence. The introduction of new products in Australia, Canada, Mexico, India, and Brazil has made the company have a significant presence worldwide. The growth is indicative of the strategic direction of Allurion of providing innovative and minimally invasive solutions to enhance the quality of gastrointestinal (GI) care and assist with obesity management by providing innovative and technologically advanced methods of treatment.
Plainly speaking, Smith and Nephew announced its enabling technologies in its INTELLO Connected Tower Solution in April 2021, such as 4KO arthroscopes and laparoscopes as well as the DOUBLEFLO Inflow / outflow Pump. These inventions aim at increasing visualization of surgery and efficiency in fluid management and also assisting the surgeons to meet a broad spectrum of patient needs more precisely and with increased control of the procedure.
These product introductions and technology applications are allowing the manufacturers to expand the market they can serve, enhance their muscle in the premium segments of hospitals, and climb the value chain by providing sophisticated visualization and less invasive solutions.
Meet the Team
This report was prepared by our expert analysts with deep industry knowledge and research experience.
Research Analyst at Custom Market Insights, specializing in market research, competitive analysis, industry trends, and growth opportunities. Focused on transforming complex data into actionable insights that drive strategic decision-making and business growth.
Table of Contents
Explore the chapters covered in the full report.
Chapter 1. Report Introduction
- 1.1 Report Description
- 1.1.1 Purpose of the Report
- 1.1.2 USP & Key Offerings
- 1.2 Key Benefits For Stakeholders
- 1.3 Target Audience
- 1.4 Report Scope
Chapter 2. Market Overview
- 2.1 Market Definition & Scope
- 2.2 Key Market Takeaways
- 2.3 Market Snapshot
Chapter 3. Market Dynamics (DRO)
- 3.1 Drivers
- 3.2 Restraints
- 3.3 Opportunities
- 3.4 Market Trends
Chapter 4. Brazil Endoscopy Devices Market - By Product
- 4.1 Endoscopes
- 4.2 Endoscopy Visualization Systems
- 4.3 Endoscopy Visualization Component
- 4.4 Operative Devices
Chapter 5. Brazil Endoscopy Devices Market - By Application
- 5.1 Gastrointestinal (GI) Endoscopy
- 5.2 Laparoscopy
- 5.3 Obstetrics/Gynecology Endoscopy
- 5.4 Arthroscopy
- 5.5 Urology Endoscopy (Cystoscopy)
- 5.6 Bronchoscopy
- 5.7 Mediastinoscopy
- 5.8 Otoscopy
- 5.9 Laryngoscopy
Chapter 6. Brazil Endoscopy Devices Market - By End‑use
- 6.1 Hospitals
- 6.2 Ambulatory Surgery Centers/Clinics
Chapter 7. Brazil Endoscopy Devices Market - Regional Analysis
- 7.1 North America
- 7.2 Europe
- 7.3 Asia Pacific
- 7.4 Middle East & Africa
- 7.5 Latin America
Chapter 8. Competitive Landscape
- 8.1 Market Share Analysis
- 8.2 Company Benchmarking
- 8.3 Strategic Developments
Chapter 9. Company Profiles
- 9.1 Boston Scientific Corporation
- 9.2 Johnson and Johnson
- 9.3 Medtronic plc
- 9.4 KARL STORZ
- 9.5 Olympus Corporation
- 9.6 Conmed Corporation
- 9.7 Smith and Nephew PLC
- 9.8 Fujifilm Holdings Corporation
- 9.9 Richard Wolf GmbH
- 9.10 Stryker Corporation
Chapter 10. Research Methodology
- 10.1 Research Approach
- 10.2 Data Collection & Sources
- 10.3 Market Estimation & Forecasting
- 10.4 Data Validation & Triangulation
Chapter 11. Standard Report Commercials & Add-Ons
Chapter 12. List Of Figures
Chapter 13. List Of Tables
Company Listing
- Boston Scientific Corporation
- Johnson and Johnson
- Medtronic plc
- KARL STORZ
- Olympus Corporation
- Conmed Corporation
- Smith and Nephew PLC
- Fujifilm Holdings Corporation
- Richard Wolf GmbH
- Stryker Corporation
Market Segments
The Brazil Endoscopy Devices Market is segmented as follows:
By Product
Endoscopes
Endoscopy Visualization Systems
Endoscopy Visualization Component
Operative Devices
By Application
Gastrointestinal (GI) Endoscopy
Laparoscopy
Obstetrics/Gynecology Endoscopy
Arthroscopy
Urology Endoscopy (Cystoscopy)
Bronchoscopy
Mediastinoscopy
Otoscopy
Laryngoscopy
Other
By End‑use
Hospitals
Ambulatory Surgery Centers/Clinics
Other
Frequently asked questions
What are the driving forces that matter the most in the market development?
Which region is the most promising in terms of CAGR?
What will be the region that is likely to assume the market?
What will be the size of the market at the end of the forecasting period?
How does price impact on market growth?
What about the role of the government regulations?
Who are the key players in the Brazil Endoscopy Devices market?
Need a tailored view of this market?
Ask our analysts to adapt the scope for your priority geographies, competitive set, customer segments, or strategic questions.
Request Customisation → Request a Sample