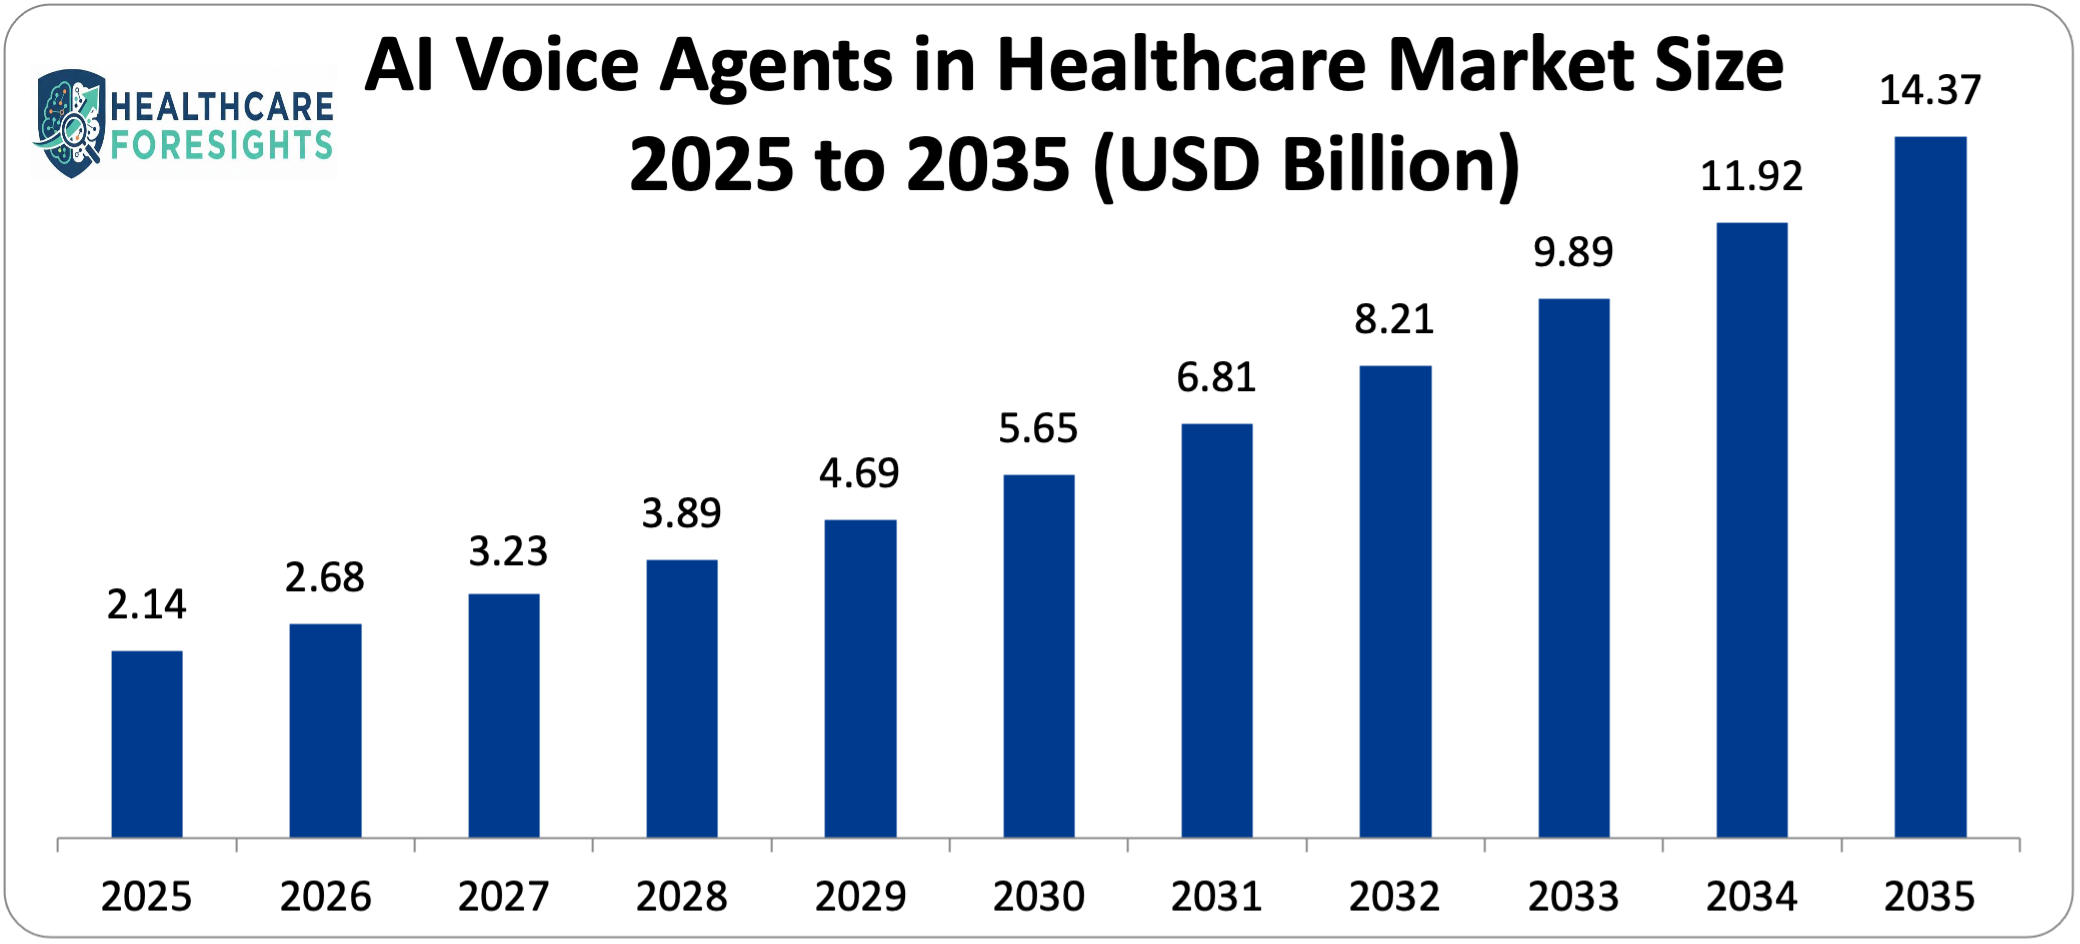
The global AI voice agents in the healthcare market value are estimated at USD 2.14 billion in 2025 and projected to move between USD 2.68 billion in 2026 and USD 14.37 billion in 2035 with an increase of 18.3% in the period between 2026-2035.
The rising use of AI-enabled voice functionality to solve the endemic physician burnout crisis caused by documentation load, the increasing use of conversational AI to interact with patients and monitor them, the swift proliferation of capabilities of large language models that can mimic clinical-grade natural language understanding and generation, the increasing regulatory clarity in the use of AI-enabled clinical software by the FDA and other health technology assessment agencies, and the attractive payoff of ambient clinical intelligence deployments in reducing physician administrative time all uphold a robust and sustainable market growth over the forecast period.
North America was the highest AI voice agent in the healthcare market, with a market share of 44% in 2025.
Asia Pacific will have the highest CAGR of 22.4% in the period 2026–2035.
By part, the software segment was able to capture about 58% of the market share in the year 2025.
By component, the services segment is projected to increase at the highest CAGR of 20.1 between 2026 and 2035.
The natural language processing segment had the largest market share of 42% in the year 2025, with the automatic speech recognition segment likely to grow with the highest CAGR of 19.8% and projected to be between 2026 and 2035.
By application, the clinical documentation and transcription segment will hold the largest market share of 36% in 2025, whereas the patient engagement and virtual assistants’ segment is likely to achieve the greatest CAGR of 21.6% between 2026 and 2035.
By end-user, the hospitals and health systems segment took up 52% of the market share in 2025 with the home healthcare segment projected to have the highest CAGR between 2026 to 2035 of 24.3%.
The AI Voice Agents in Healthcare Market Trends present significant growth opportunities due to several factors:
The most influential and implementable structural force of AI voice agent uptake in a clinical environment, and the strongest and most urgent at the same time, is the globally spread and increasing crisis of physician burnout, in which the administrative documentation load is uniformly cited as the greatest contributor, whereas clinical ambient intelligence systems that produce clinical notes as a result of physician-patient conversation recordings will reduce the most time-intensive and professionally de-motivating part of the contemporary physician workload without necessitating modification of the clinical workflow. A 2023 survey by the American Medical Association found that more than half of U.S. physicians had at least one of the symptoms of burnout, with the high age being significantly higher among primary care physicians and emergency medicine physicians than among other medical specialties because of the high volume of documentation relative to time available, electronic health record documentation was found to be the major factor in most cases of burnout.
The volume of administrative documentation in contemporary clinical practice is significant and quantifiable: in the articles published in the Annals of Internal Medicine and JAMA, it was established that physicians spend about 12 hours of documentation per hour of patient care, and primary care physicians spend about 4-6 hours of documentation per day in EHR, which occupies time that could otherwise be used on patient care, professional development, or personal relaxation. Directly solving this time burden, ambient clinical intelligence platforms, where the AI voice agent technology hears the physician-patient clinical interaction, interprets the clinical content of the interaction using the large language model of natural language processing, and automatically writes a structured clinical note to the standards of documentation in the healthcare organization, remove the manual transcription work by the physician after patient interactions.
The ambient clinical intelligence platform, DAX Copilot, most widely deployed by Microsoft Nuance, has published the results of health system implementations that have cited that physicians using the system finish clinical documentation 50-70% faster than through dictation or manual entry, save 1-3 hours per clinic day previously spent on documentation, and have significantly improved physician satisfaction with work and end-of-day documentation burden. The economic benefit of this productivity gain is simply overwhelming: a primary care physician who recovers 2 hours of clinical time per day is in a position to see 4-6 more patients, resulting in USD 400000-USD 800000 of extra annual income at average primary care reimbursement rates - an economic argument in which the cost of an ambient clinical intelligence subscription fee of USD 500-USD 1500 per physician per month will pay back in weeks, not years.
Expanding Telehealth and Remote Patient Monitoring Creating Voice AI Patient Engagement Demand: The expansion of telehealth as a permanent feature of healthcare delivery as virtual care visits are continuing to be sustained is significantly higher than the same functions were pre-pandemic in most developed healthcare systems, and the rapid growth of remote patient monitoring programs to manage chronic patient diseases is creating significant new demand on AI voice agent patient engagement capabilities that can scale patient communication, monitoring, and care coordination functions to ineffective staffing ratios in the human care team. The COVID-19 pandemic created an unprecedented speed of telehealth use - with U.S. telehealth use nearly 38 times higher in April 2020 than at the pre-pandemic baseline, as McKinsey analysis shows - and as utilization stabilized as in-person care re-emerged, telehealth visit volumes had become a structural change in care delivery that generated long-term demand for digital patient engagement tools. Remote patient monitoring programs, where patients with chronic diseases such as heart failure, diabetes, COPD, and hypertension monitor themselves using home monitoring equipment and transmit the data to clinical care teams who view it and implement interventions when the values are out of range, are rapidly scaling as the payer is reimbursing remote monitoring programs under CPT codes 99457 and 99458 to provide sustainable revenue models to operate remote monitoring programs. AI voice assistants used in remote monitoring settings - daily check-in phone calls with patients under surveillance, posing structured symptom and adherence queries, examining patient-reported answers with patient-reported clinical alert algorithms, and sending alarming feedback to clinical care team consultation — enable remote monitoring programs to maintain meaningful clinical contact with patient populations far larger than human staffing ratios would permit, with published implementations reporting AI voice agent call programs achieving patient contact rates of 85–95% at costs of USD 2–USD 8 per patient contact compared to USD 15–USD 35 for nurse-conducted telephone contacts.
What are the Major Advances Changing the AI Voice Agents in Healthcare Market Today?
Large Language Model Integration Enabling Clinical-Grade Conversational Intelligence: Incorporation of large language models, including GPT-4 and Claude and Gemini, as well as clinical language models trained on medical text, into healthcare voice agent systems has created a qualitative breakthrough in clinical language comprehension. These models transform voice agents, which are basic keyword-matching scripts, into intelligent companions that comprehend intricate medical language, offer clinical reasoning, and respond to nuanced patient dialogues. LLMs with healthcare applications, including the BioGPT by Microsoft, Med-PaLM 2 by Google, and models fine-tuned by Nuance, Suki, Abridge, and Ambience Healthcare, perform better on clinical language than general-purpose LLMs. They are close to the accuracy of expert physicians in their responses to medical questions and document their answers as the medical specialists do in systematic assessments. Creating clinical documentation is a challenging process that involves speech transcription accuracy, interpretation of the clinical sense of physician-patient dialogue, the transfer of diagnostically and therapeutically significant information, the correct application of the clinical note templates, the correct use of the medical terms, and the exclusion of irrelevant conversations. The most qualified LLMs can only be used to achieve the quality threshold required in clinical deployment. Published reviews oppose AI-generated notes against physician-written gold notes on traditional quality rubrics. The best platforms, such as Nuance 2.0 DAX, Abridge, and Suki, have the quality of notes as good as the physician-written notes. AI notes are usually better than physician reviews because of completeness and consistency. The improvements in the medical language understanding, clinical reasoning, and documentation quality are measured with each new generation of LLM. Such a steep enhancement in performance results in annual growth in performance, inducing its uptake as clinical quality benchmarks are achieved in more challenging specialties and settings.
Multimodal Clinical AI Integration Combining Voice with Clinical Data: AI voice agents in healthcare are becoming more of a multimodal system, rather than a voice-only system. They integrate the voice knowledge with real-time access to EHR data, imaging, lab data, medication data, and decision-support knowledge bases and provide more valuable and context-aware clinical support than voice. The Next-generation ambient system hears what is said to the patient, retrieves the complete EHR of the patient, and applies decision-support logic to the discussion and data. They are capable of notifying physicians of interactions with drugs, screenings, abnormal labs, and dosages without making them manually review during time-sensitive encounters. The ambient AI of Epic is the integration of Nuance DAX and in-context access of EHR, and the voice-activated assistant of Oracle Health signifies the other innovative applications. These platforms are implemented by hundreds of large health systems, which have interoperable Epic or Oracle EHR frameworks. The multimodal voice AI diagnostic support listens to the description of the exam provided by the physician and automatically retrieves the relevant history and presents the differential diagnoses based on knowledge bases. Firms such as Suki AI and Ambience Healthcare are no longer in research but early clinical uses, where real-time decision support is based on ambient documentation. Multimodal agents facing the patient apply the EHR data to provide customized medication reminders with drug names and dosages, prep instructions before appointments, and customized post-discharge care plans based on the diagnosis and treatment.
Voice AI-Enabled Medication Management and Adherence Support: The voice agent-based medication management system (such as automated medication reconciliation throughout encounters, conversational adherence, refill coordination, and pharmacist-patient counseling) is a high-impact, fast-growing market that addresses medication non-adherence, which is a cost burden in healthcare. WHO estimates that non-adherence occurs in approximately half of long-term patients. It causes preventable deaths, diseases, and avoidable hospitalization, which cost the U.S. 100-300 billion a year (Annals of Internal Medicine). In adherence programs, AI voice agents make automated calls or answer queries raised by the patients, overcoming the barriers of confusion in dosing, side effects, and financial barriers with personalized, real-time assistance that does not need pharmacy staff effort. Programs of Orbita Healthcare, Conversa Health, and Rx.health have been studied, with the adherence improvements of 10-20 percentage points compared to regular care and resulting in quantifiable decreases in disease-related hospitalizations and ED visits. AI voice agents connected to pharmacy benefit data generate real-time medication reconciliation in the clinics. They identify inconsistencies among the lists of patients and dispensing records, alert to an unfilled prescription, and potentially suggest drug-drug interactions. This reduces the 30 minutes of reconciliation burden on nurses and physicians in the admission process.
By Component
Why Does Software Lead the Market?
Software is the largest component segment with an estimated 58% of the total market share in 2025, as the intensity of intellectual property that is developed in the development of clinical AI voice agents is substantial, with the LLM fine-tuning of clinical corpora, healthcare-specific model development, EHR integration middleware, clinical workflow automation logic, and user interface engineering being years of specialized development investment and priced at a premium subscription price, not the underlying hardware infrastructure. Clinical AI voice agent software platforms such as Microsoft Nuance DAX Copilot, Suki AI, Abridge, and Ambience Healthcare are sold as subscription-based SaaS systems on a per-physician or per-facility, per-month basis that create highly predictable recurring revenue streams as clinical users become more active. The superiority of the software segment is supported by the continuous improvement value of AI voice agent platforms - whereby the performance of the model can be enhanced by continuous training on increasing clinical data corpora, providing new specialty-specific documentation templates, and compatibility of new modules with the application platform that creates an increasing return on subscription investment that sustains renewal and upsell in existing accounts. The movement toward enterprise health system contracts, where voice agent platform solutions are purchased by full physician organizations, not by individual physician subscriptions, is both releasing higher average values of contracts and placing software segment revenue in the hands of the largest platform providers with the enterprise sales, implementation, and account management capabilities needed to work with large health system customers.
By Technology
Why Does Natural Language Processing Lead the Market?
Natural language processing is the highest technology component, with about 42% of the overall market share in 2025, in recognition of the enabling technology that enables NLP to differentiate the voice agent-based AI versus simpler speech recognition and transcription systems, which is the ability to provide semantic interpretation of clinical language and disambiguate medical terminology, infer and give structure to the information, and convert spoken clinical dialogue into actionable clinical records and decision support. Healthcare NLP contains a number of technically challenging capabilities not found in general-domain NLP: medical named entity recognition that finds the diseases, medications, procedures, and anatomical structures in unstructured clinical language; clinical relationship identification that finds the logical associations between the identified entities; negation and speculation that properly supports the "no chest pain" and rule out pneumonia" constructions that pervade clinical documentation; and section classification that properly routes the extracted information to the appropriate EHR documentation locations. The clinical NLP features of major AI voice agent systems are trained on large corporate corpora of clinical documentation, physician orders, and clinical literature that are not public and reflect the greatest technical moat protecting major platform providers against commodity competition and explain why companies such as Microsoft Nuance, Google Health, and Anthropic continue to invest in R&D companies to develop clinical NLP model functionality.
By Application
Why Does Clinical Documentation & Transcription Lead the Market?
Clinical documentation and transcription, including ambient clinical intelligence to generate physician notes, clinical coding support, and medical transcription, do represent the largest application segment at nearly 36% of total market share in 2025 reflecting the combination of the largest addressable market in any healthcare AI voice app, the most measurable and quantified return on investment through initial implementations, and the most organizational sense of urgency achieved through the physician burnout crisis that documentation burden reduction will be at the C-suite healthcare executive level of priority. The clinical documentation application enjoys the longest history of technology readiness of any AI voice agent healthcare application, with ambient clinical intelligence platforms having gone through multiple product generations since initial deployments in the late 2010s, the clinical training data, specialty-specific model fine-tuning, and integration infrastructure into EHRs that make these applications reliable to deploy in a wide range of clinical settings and specialties. The most commercially developed ambient clinical intelligence platform in the world is Microsoft Nuance DAX Copilot, deployed at numerous large health systems such as Sutter Health, Providence Health, and Mercy Health, and hundreds of other customers (health and non-health) worldwide, published implementation outcomes have indicated a reduction in documentation time of 50-70% plus high scores on physician satisfaction, which leads to rapid word-of-mouth adoption by physician organizations once established as successful.
By End-User
Why Do Hospitals & Health Systems Lead the Market?
Hospitals and health systems are the largest end-user segment in 2025, as they represent a combination of the largest physician and clinical staff populations, most likely to generate the greatest documentation load and benefit the most from ambient clinical intelligence, and has the organizational scale and financial resources to implement the ambient clinical intelligence platform in its most extensive applications, the EHR system infrastructure (most commonly Epic, Oracle Health, and Meditech, with which AI voice agents must interface to be embedded into clinical workflows), and the strategic direction of health system leadership towards physician retention and burnout reduction as a The fact that AI voice agent adoption is concentrated in large health systems, with these organizations such as Kaiser Permanente, Mayo Clinic, Cleveland Clinic and Intermountain Health among the most progressive early adopters, means that the organizations are combining technical sophistication, investment in innovation, and a sizable physician base that would warrant the enterprise contract values and implementation investments to deploy AI voice agents on a large scale. The types of contracts that are considered the largest and most strategically vital sources of revenue to providers of AI voice agent platforms include health system enterprise contracts of ambient clinical intelligence, which include multi-year subscription contracts of USD 2 - USD 20 million annually based on the population of physicians and the scope of the platform.
Report Scope
Feature of the Report | Details |
Market Size in 2026 | USD 2.68 billion |
Projected Market Size in 2035 | USD 14.37 billion |
Market Size in 2025 | USD 2.14 billion |
CAGR Growth Rate | 18.3% CAGR |
Base Year | 2025 |
Forecast Period | 2026-2035 |
Key Segment | By Component, Technology, Application, End-User and Region |
Report Coverage | Revenue Estimation and Forecast, Company Profile, Competitive Landscape, Growth Factors and Recent Trends |
Regional Scope | North America, Europe, Asia Pacific, Middle East & Africa, and South & Central America |
Buying Options | Request tailored purchasing options to fulfil your requirements for research. |
How Big is the North America Market Size?
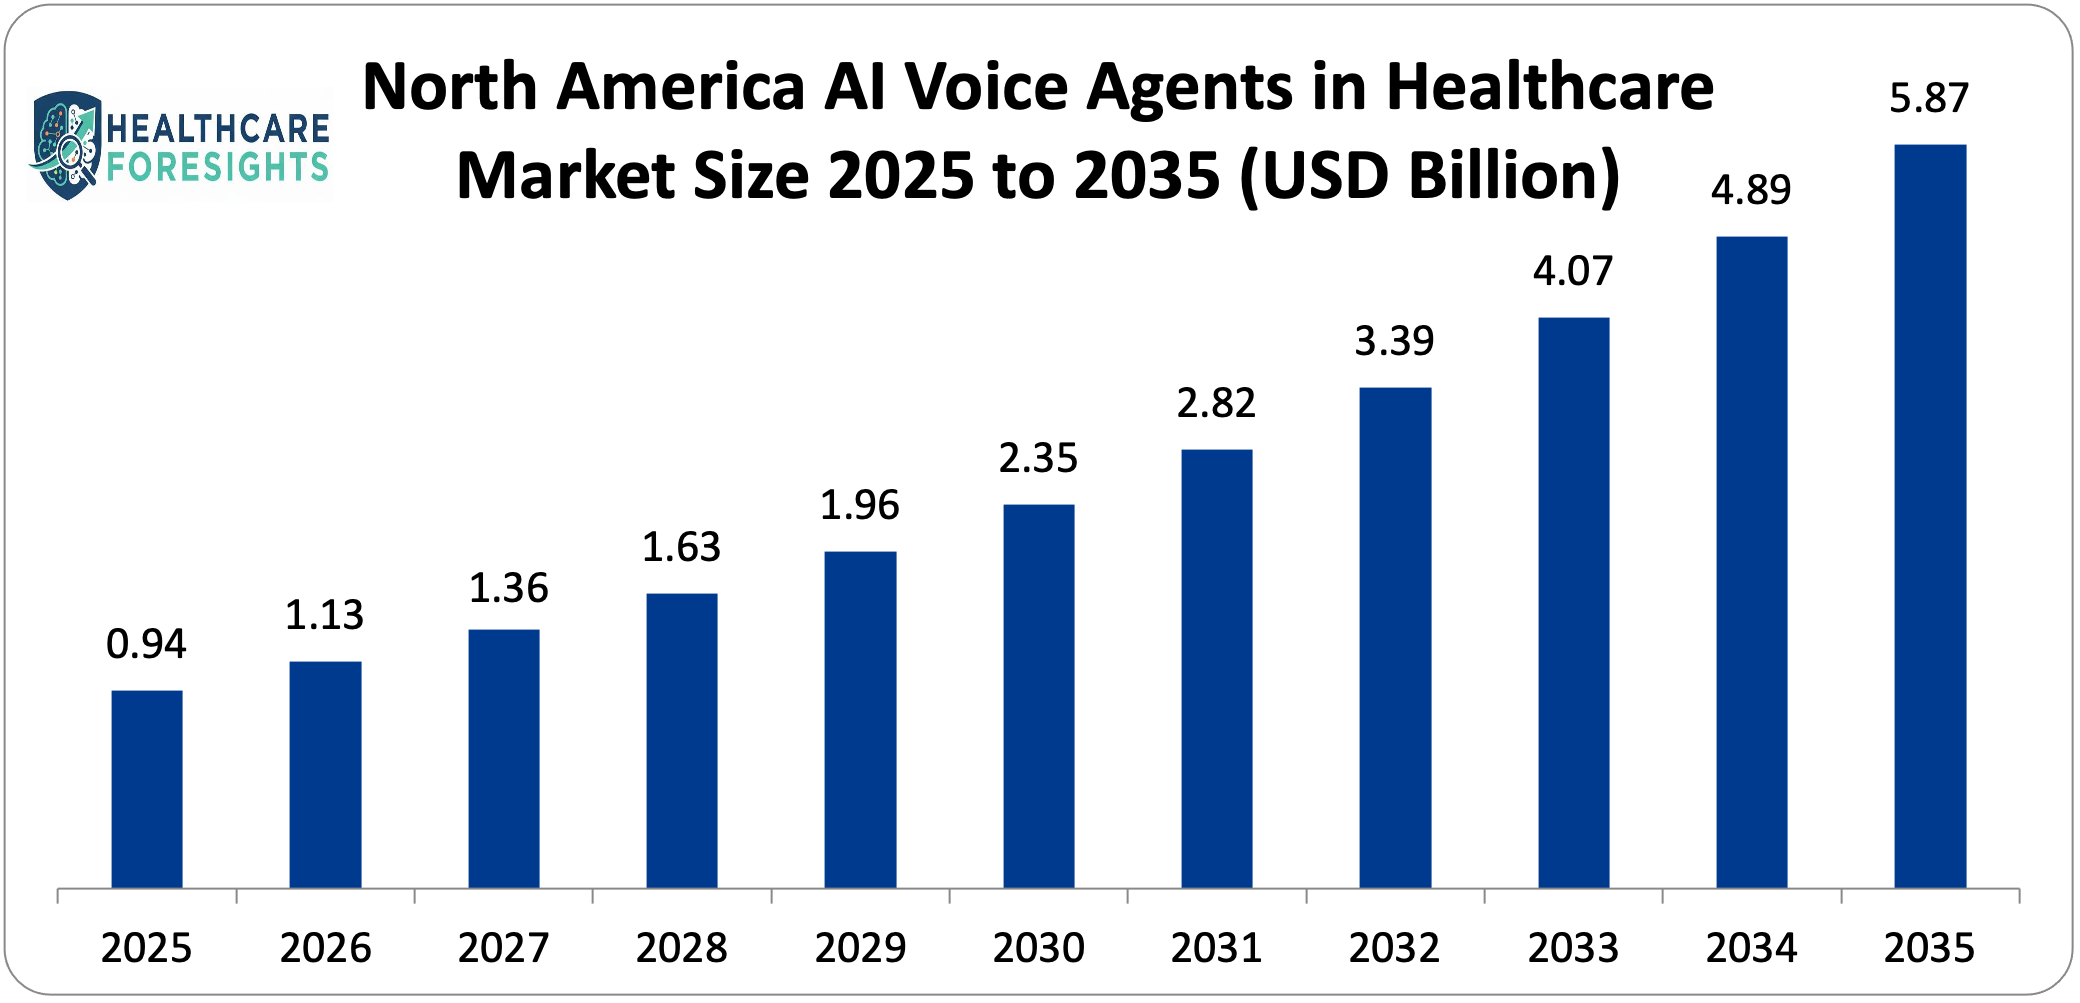
The North American AI voice agents in healthcare market size is estimated at USD 942 million in 2025 and is projected to reach approximately USD 5.87 billion by 2035, with a CAGR of 20.1% from 2026 to 2035.
Why Did North America Dominate the Market in 2025?
In 2025, North America controls about 44% of the world market share, which is the influence of the United States as the largest investment market in healthcare AI around the world, as the combination of high physician pay and the scale of the healthcare system makes documentation time recovery in the U.S. healthcare system one of the most extraordinary financial value, the largest EHR system installation in the world offers the industry the data infrastructure where AI integration can be implemented, the well-established venture capital/technology company ecosystem has created the most successful AI voice agent platform companies, and regulatory clarity.
The U.S. physician workforce (of about 1 million actively practicing physicians as reported by the Association of American Medical Colleges) is the largest among any potentially addressable market of ambient clinical intelligence in the world and, collectively, has USD 500 million-USD 1.5 billion of annual subscription revenue to ambient intelligence in the United States alone. This tendency towards the concentration of major AI voice agent healthcare companies, such as Microsoft Nuance, Suki AI, Abridge, and Ambience Healthcare, in the United States is an indicator of the strength of the AI technology ecosystem, healthcare domain concentration, and access to clinical data partnerships with major health systems in the United States used to develop clinical AI models. The active efforts of the American Medical Association to promote technology solutions to the issue of physician burnout, with the AMA's STEPS Forward program facilitating ambient AI clinical documentation as one of the recommended practice improvement initiatives, are hastening physician awareness and uptake of AI voice agent clinical documentation solutions into the U.S. physician community.
Why is Europe a Strategically Important Market?
The European AI voice healthcare market is projected to be about USD 578 million in 2025 and is projected to be about USD 3.16 billion in 2035 with a CAGR of 18.5%. The European region is a strategically important market due to the National Health Service's active clinical documentation program based on AI use in the United Kingdom, Active AI clinical documentation implementation agenda by NHS England, which expressly includes ambient clinical documentation as a priority technology in terms of reducing administrative clinician burden in the United Kingdom, and the culture of progressive healthcare AI adoption in the Nordics, with the example of the integrated national health data infrastructure in Denmark and Sweden (which will support AI training and validation at population scale). The European Health Data Space project by the EU, an initiative to facilitate health information exchange among EU member countries to facilitate AI development and implementation, is developing the data access infrastructure on which the companies that provide AI voices in Europe can create and test clinical AI models on European patient population datasets, facilitating the creation of European market-specific clinical AI features. The NICE Early Value Assessment system of AI medical devices in the UK - which offers expedited routes to the market for AI medical devices that meet particular clinical evidence criteria - is facilitating faster NHS implementation of reviewed AI voice agent solutions, which provides a more regulatory-friendly environment for the early adoption of AI clinical technology than the conventional NICE appraisal route.
Why is Asia Pacific the Fastest-Growing Market?
The fastest-growing regional market is Asia Pacific, which has a CAGR of 22.4% between 2026 and 2035 due to the sudden rapid digital transformation of healthcare systems in China, India, Japan, South Korea, and Australia, the acute shortage of physicians in most of the Asian healthcare systems that makes AI-enabled clinical workflow and automation of the workflow in particular especially appealing as a force multiplier of constrained physician capacity, and the increasing number of people seeking healthcare services in the region that creates scale effects demanding AI-enabled clinical efficiency. India is also an especially interesting growth market based on the fact that the acute physician-to-population ratio of the country is so low that WHO data indicates, at 1.3 physicians per 1,000 population, it severely lacks in this aspect when compared to the WHO-recommended norms, which stand at a minimum of 1.3 physicians per 1,000 population. The fast evolution of the Indian health technology market, with healthtech getting substantial venture funding and resulting in companies such as Augnito (clinical speech recognition), Niramai, and SigTuple, is providing native AI voice agent functionality to meet Indian clinical care practices, local language needs, and the particular documentation needs of Indian healthcare systems (both public and private).
Why is the Middle East & Africa Region an Emerging Opportunity?
The LAMEA region is evolving with increasing market development due to the ambitious healthcare digitalization investment initiatives of the Gulf Cooperation Council, such as the Saudi Arabian Vision 2030 healthcare transformation project aiming at developing a world-class digital health infrastructure; the UAE AI strategy making the country a leading global AI hub with healthcare among its priority areas of application; the region's high rate of internationally trained physicians knowing AI clinical documentation tools used during their training environments; the increasing medical tourism industry in Dubai and Abu Dhabi that demands the highest level of clinical efficiency and quality of documentation; and the substantial size of Brazil's substantial private healthcare sector with growing AI adoption investment among leading private hospital groups, including Hospital Albert Einstein, Hospital Sírio-Libanês, and Rede D'Or.
The market has seen major changes, with industry players aiming to develop large language model clinical services, increase the use of enterprise health systems, and address higher global demand for AI-driven solutions to the problem of physician burnout and scalability of patient interaction.
In November 2024: Microsoft Nuance declared the general accessibility of DAX Copilot incorporated directly into the Epic EHR interface, thus allowing ambient clinical documentation to operate smoothly within the current Epic workflow of the physician without the need to switch applications.
In October 2025: Abridge AI declared a USD 150 million Series C funding round directed by Spark Capital and including current investors such as Bessemer Venture Partners and Union Square Ventures and valued the company at USD 850 million, positioning Abridge as one of the most highly valued independent clinical AI voice agent enterprises in the globe.