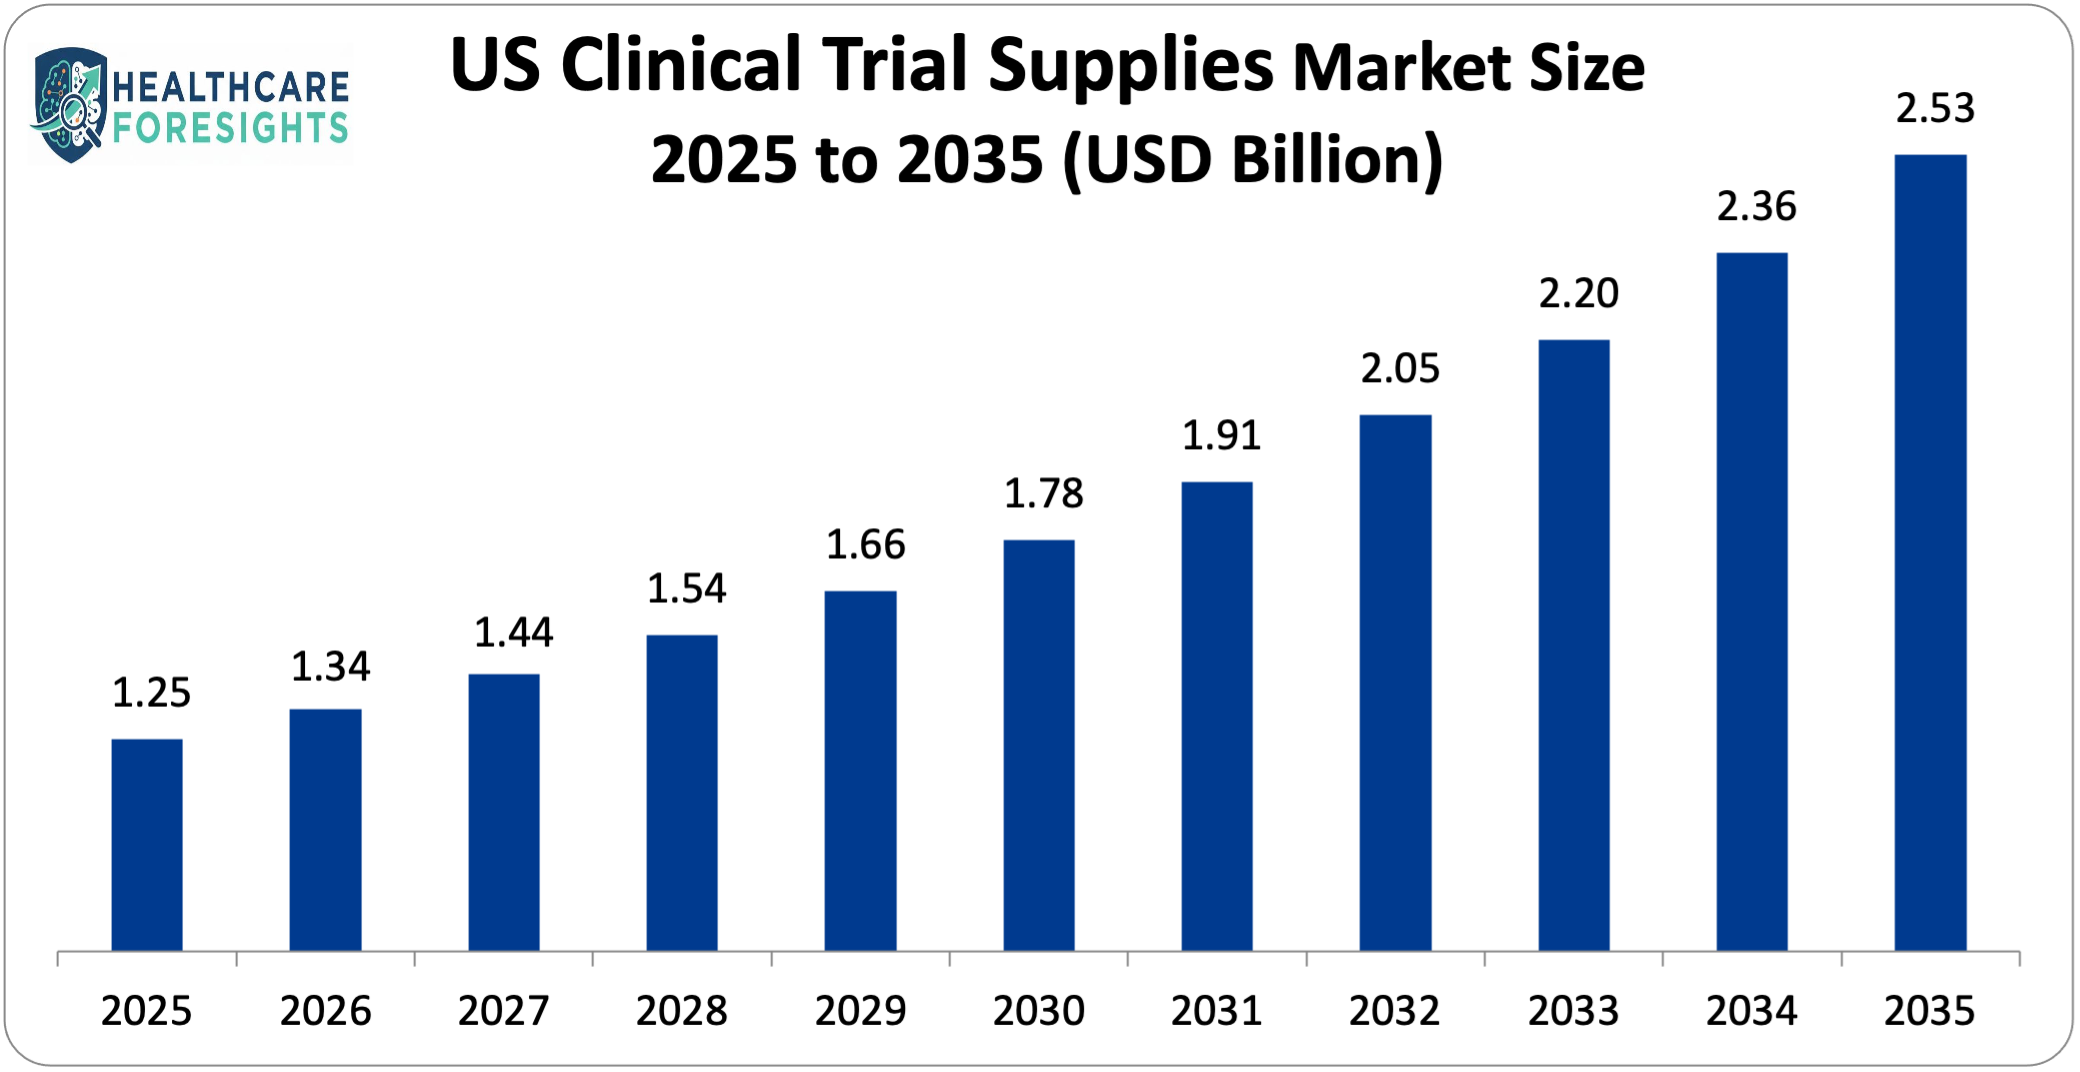
The U.S. clinical trial supplies market is valued at approximately USD 1.25 billion in 2025, expected to reach nearly USD 1.34 billion in 2026, and projected to grow to around USD 2.53 billion by 2035, expanding at a CAGR of 7.4% from 2026 to 2035. Market growth is primarily driven by the rising number of clinical studies across pharmaceuticals, biologics, and advanced therapies, along with increasing complexity in trial designs requiring efficient sourcing, packaging, and global distribution of investigational materials.
Expansion of decentralized and hybrid clinical trials, growing demand for direct-to-patient delivery models, and heightened focus on regulatory compliance and temperature-controlled logistics are further supporting market development. Additionally, strong R&D investments by U.S.-based biopharmaceutical companies, rapid growth in oncology and rare disease trials, adoption of digital supply chain management systems, and increasing outsourcing to specialized trial supply service providers are expected to accelerate market expansion throughout the forecast period.
Under the under-supply type, the share of investment health products and ancillary supplies in the total market revenue is projected to increase more than 38.8% by 2025, due to their necessity in the implementation of the trials and dosing of patients.
By trial, the Phase III trials are expected to increase at a CAGR of 7.6% between 2026 and 2035 due to the increasing level of late-stage drug development and volumes of patients enrolled in trials.
According to the service model, full-service providers had approximately 41.6% of the market share in 2025 as the sponsors start outsourcing entire supply chain operations.
Oncology was one of the therapeutic groups that had the highest contribution to total revenue of about 48.5% by 2025, considering the high number of cancer research programs in the U.S.
Under the distribution strategy channel, the direct-to-site delivery is expected to generate approximately 39.5% of market revenue in 2025 because of its quicker site activation and effective logistics management.
Pharmaceutical companies dominated the market share with almost 48.6% among the end users in 2025 by the size of their R&D-based investment and a large clinical pipeline.
Expansion of Decentralized and Hybrid Trial Models: Decentralized and Hybrid Trial Models are rapidly expanding in the United States as sponsors and clinical research organizations are reassessing these trial models to improve patient access and retention. Grants: Over 70 percent of the new late-phase trials have some decentralized aspect (e.g. remote patient monitoring or delivering supplies at home). This has strongly increased the necessity of clinical supply solutions that will support direct-to-patient (DTP) distribution, temperature-controlled deliveries, and pre-prepared patient packages, particularly in trials that are performed in oncology, immunology, and rare conditions.
The growth of cold-chain logistics is facilitated by an Increase in Trials of biologics and complex molecules: Trials of biologics (as well as complex molecule trials) are growing at a very high rate, and more than 40 percent of active clinical protocols will be biologics trials by 2024 (based on available public clinical trials registries). These are generally sensitive to stringent temperature conditions (2°C - 8°C or -20°C or -80°C) during storing and shipping. Respondents in the form of sponsors and logistics have in turn augmented cold-chain infrastructure in response to this and have invested in IoT-related thermal packaging and real-time temperature monitoring as a mechanism to ensure product integrity between central laboratories and trial sites/patient homes.
Improved efforts to implement Digital Supply Chain and Forecasting Equipment: There are growing efforts in the use of technology in the clinical supply chain. The introduction of electronic inventory management systems, RFID tracking and cloud based demand forecasting systems by the service providers and large sponsors has become a common practice in an attempt to minimize stockouts and maximize batch allocations at the different sites. Overstocking is expected to be minimized by about 15-20 percent in the case of numerous trial product investigations or sophisticated randomization where real-time visibility lowers waste and overheads to reduce operational costs.
What Are the Major Enhancements that are Changing the U.S. Clinical Trial Supplies Market?
The Construction of Regulatory Controls and Trial Compliance Requirements: Federal or government agencies in the U.S. like the FDA and OHRP have made the rules more stringent in terms of the management, storage and delivery of the investigational products. The sponsors and clinical research organizations (CROs) should make sure that there is improved traceability of batches, storage under controlled temperature and electronic documentation of clinical supplies. As a result, more than 65 percent of phase II and III trials since 2023 have utilized better supply management software and ensured cold-chain logistics that minimize the deviations in protocols and protect the integrity of the products during the trial process.
Technological Supply Chain Management Innovations and Patient-Centric Delivery: U.S. clinical trial sponsors are urgently adopting digital supply chain solutions, AI-based demand forecasts and shipment tracking in real time to enhance inventory and efficiency of sites. There is a rise in direct-to-patient (DTP) supply systems and decentralized trial models and it has been reported that more than 40% of late stage oncology trials and rare disease trials are currently using home delivery kits. The developments have led to shortened lead times for supplying the investigational products to the patients and improvement of the patients' adherence and have made the trials to be conducted faster without jeopardizing the Good Clinical Practice (GCP) standards.
Strategic Collaborations, Outsourcing, and Localized Service Networks: Due to the increasing popularity of outsourcing between large CROs and logistics service providers and pharmaceutical companies as a way to offer a full service of clinical supply, including kit assembly, labeling and controlled temperature delivery, strategic alliances are becoming popular. In locations like Boston, San Diego and the Research Triangle, nearly fifty percent of the active clinical trial sites obtain their supplies via local depots and save enduring times by as much as fifty percent, contrasting the central distribution paradigm. These working arrangements are also inclusive of the long-term service arrangements, site training arrangements, and adaptive replenishment initiatives that help sponsors with complex trial protocols and expand the trial to urban and semi-urban locations.
By Service Model
Why then are full-service providers so dominating?
Full-service providers are those that deal with end-to-end supply chain operations such as kit assembly, labelling and distribution. They unearth favourable complex multi-site or global trials to sponsors since they are supportive to compliance and efficiency.
Why are functional service providers becoming famous?
Functional service providers focus on remote components of the supply chain (e.g. cold-chain logistics service or labeling service) so that sponsors can save money and still control key processes.
Why should hybrid models be advantageous?
The hybrid service models hybridize the full-service and functional models that provide adaptive and decentralized trial solutions that are flexible and scalable.
By Therapeutic Area
What makes the oncology the largest therapeutic segment?
Oncology trials are more complex biologics and large volumes of patients demanding greater IMPs, lab kits, and patient kits. The growing supply chain needs are also augmented by the growing numbers of targeted therapies.
Why does research on infectious diseases have an impact on the needs of supplies?
The vaccines and antiviral studies have to be done in a cold chain besides being delivered promptly to different study locations. The more action is in this sector, the more logistics investment in temperature control is triggered.
What occurs in the market due to the rare disease trials?
When conducting research on rare diseases, there will be a high demand for patient-centric kits, special packaging, and delivery of DTP. These trials are highly complex, and this complicates the supply chains.
By Distribution Strategy
The question arises as to why it is so widespread to deliver directly to sites?
The trials that are performed in hospitals are usually delivered on-site because direct-to-site deliveries are extremely important in the transfer of controlled materials and compliance with the regulations. On this model the timely supply of IMPs and lab kits occurs in large academic and commercial trial locations.
Why is there the expansion of direct-to-patient distribution?
The supply of DTP is also enhanced by decentralized experiments and home participation of patients. LABs, lab kits, and ancillaries are directly shipped to patients to increase retention and adherence.
What are the regional and central depots doing to improve logistics?
The central location of the depots helps to store in bulk and deliver to the regions at a cheaper price as well as increase inventory management. The depots on the regional level will also assist in delivering supplies closer to the trial places and patients and delivering goods quicker and reducing the chance of spoilage.
By End User
So why regulate consumption of supplies in health care industries?
Pharma sponsors carry out trial tests on high volumes in different locations, which encourages the use of IMPs, lab kits, and specialized packaging. They make their investments in innovative therapies that contribute to the supply demands even further.
What is so significant about the biotechnology companies as consumers?
Biotech companies are targeting such sophisticated treatments as gene and cell therapies; this includes cold-chain controls, patient-based packages, and regulatory-compliant packages.
How can CROs affect the market?
CROs provide sponsor supply management outsourcing that provides scalable solutions to the assembly, labeling, and distribution of kits during complex and multiple-site trials.
What do academic research institutes mean?
The ones that conduct investigator-initiated studies and small-scale trials in the early phases with small batch sizes and special supply needs, such as protocols, are academic Centers. These specialized studies demand flexibility in their supply solutions.
Report Scope
Feature of the Report | Details |
Market Size in 2026 | USD 1.34 billion |
Projected Market Size in 2035 | USD 2.53 billion |
Market Size in 2025 | USD 1.25 billion |
CAGR Growth Rate | 7.4% CAGR |
Base Year | 2025 |
Forecast Period | 2026-2035 |
Key Segment | By Supply Type, Trial Phase, Service Model, Therapeutic Area, Distribution Strategy, End User and Region |
Report Coverage | Revenue Estimation and Forecast, Company Profile, Competitive Landscape, Growth Factors and Recent Trends |
Buying Options | Request tailored purchasing options to fulfil your requirements for research. |
The U.S. clinical trial supplies market is improving with the top service providers and logistics firms building capacity and enhancing supply chains and helping to support decentralized and complex volumes of trials.
In October 2025, Thermo Fisher Scientific acquired Clario to support the provision of digital health and clinical trial services, and in January 2025, Thermo Fisher collaborated with Pfizer to introduce blockchain-based traceability to trial supplies.
Catalent, 2024: Catalent made a USD 150mm investment to increase its cold-chain infrastructure to support biologic and gene therapies in December 2024 and PCI Pharma Services established a new clinical supply facility in Rockford, Illinois in Q2 2024 to enhance packaging, labeling and distribution.
DHL International also developed IoT tracking systems in November 2024 and UPS Healthcare also announced temperature-controlled packaging on cell and gene therapy trials in Q2 2025.
Parexel International acquired a minority stake in an Indian logistics and clinical provider of logistics in October 2024, and in August 2024 Almac Group collaborated with Moderna to simplify the logistics of vaccine trials by providing better cold-chain management.
Such efforts have enhanced supply chain efficiency, enhanced cold-chain and DTP services, and enhanced increasing implementations of new logistics and patient-centric solutions throughout the U.S. clinical trial supplies market.