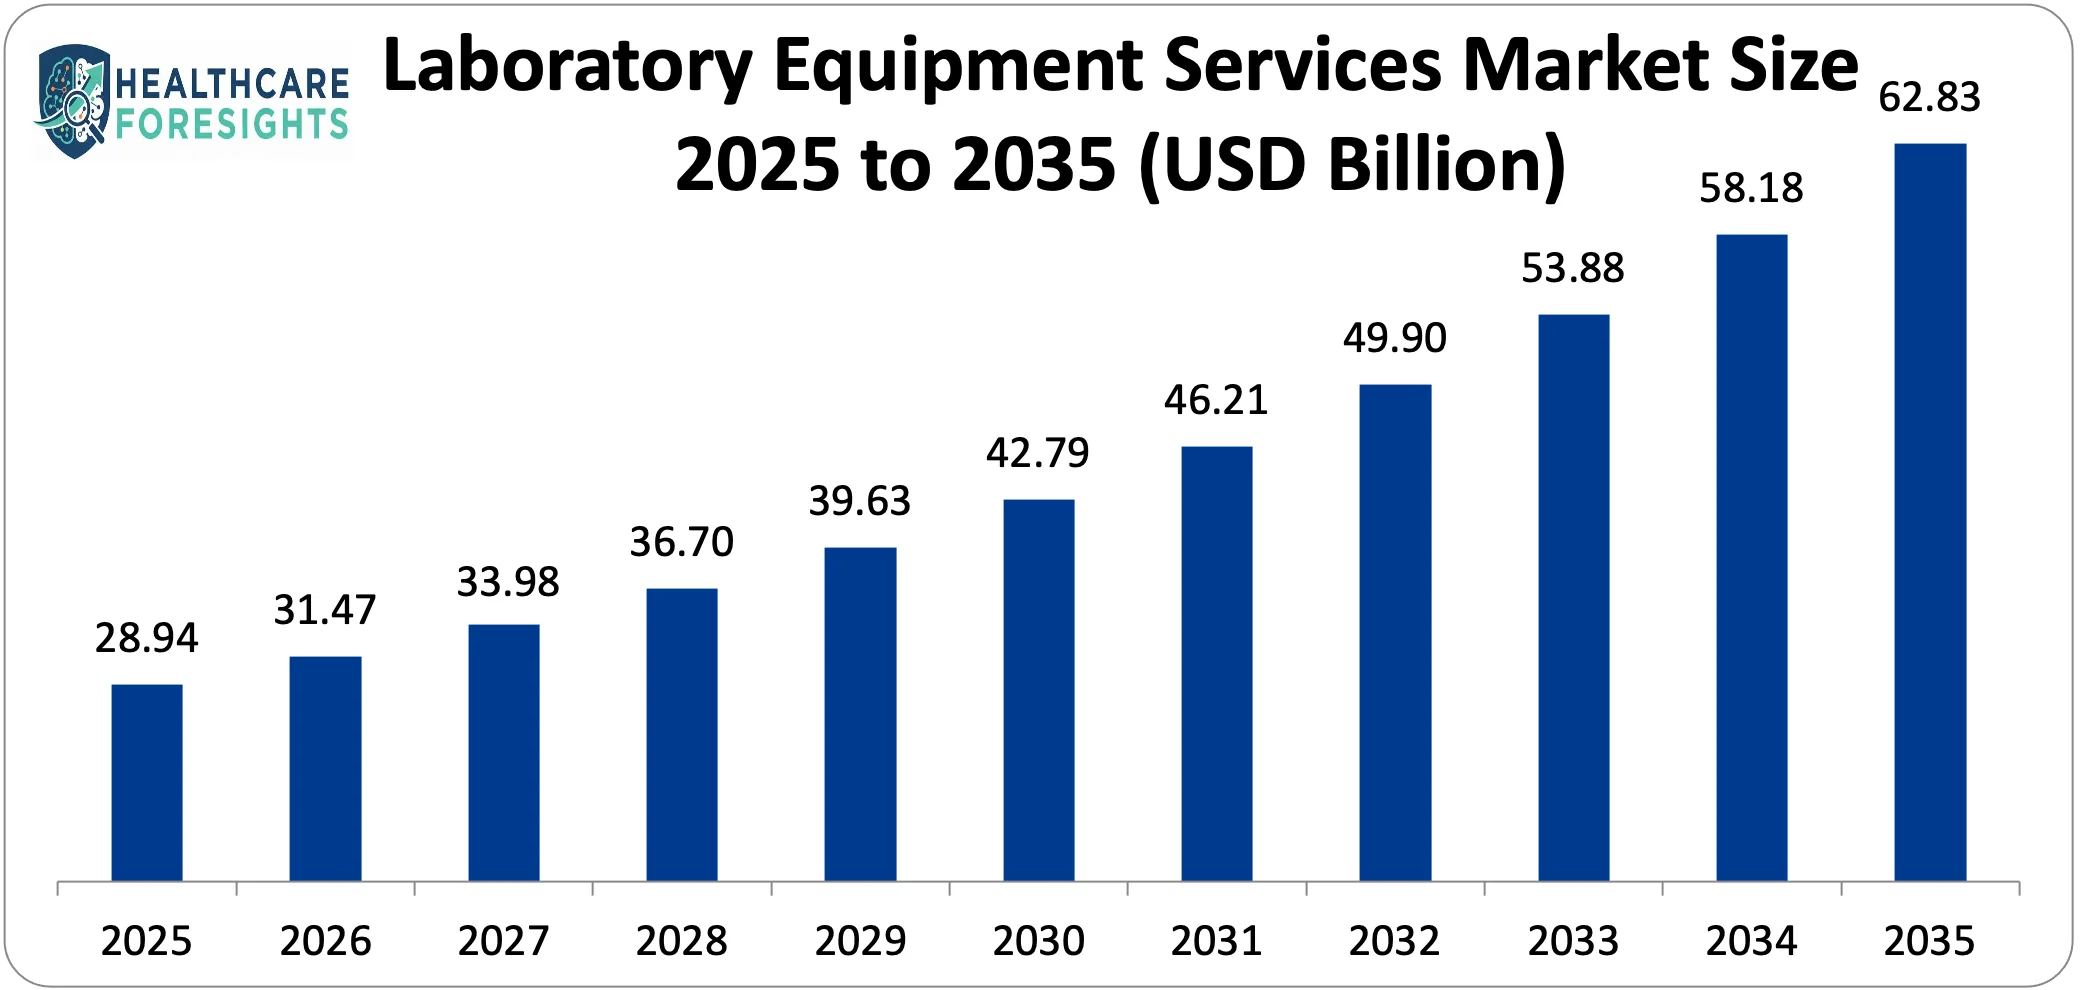
The global market size of laboratory equipment services is estimated at USD 28.94 billion in 2025 and is projected to grow to USD 31.47 billion in 2026 and grow by a CAGR of 8% in the year 2035 to USD 62.83 billion.
The slowing down of attitudes to outsourcing the maintenance of laboratory equipment, the increasing complexity and capital cost of modern analytical instruments that render professional servicing financially indispensable, the growing momentum and capital outlay to outsource laboratory equipment maintenance to specialized services, and the digitalization of service delivery through an IoT-enabled predictive maintenance and remote diagnostic solution all combine to produce a sustained and healthy market growth over the forecast period.
Asia Pacific will grow with the best CAGR of 10.4% in the period between 2026 and 2035.
The calibration services segment had about 32% of the market share by the service type in the year 2025.
By the type of service, the segment that is increasing with the highest CAGR of 10.2% is the validation services segment between 2026 and 2035.
By end-user, the pharmaceutical and biotechnology companies segment has the largest market share of 34% in 2025, whereas the food and beverage testing laboratories segment is liable to have the highest CAGR of 9.8% through the expected performance between 2026 and 2035.
By type of equipment, the segment that did 38% of the market share in 2025 was instruments of analysis.
By service provider, the OEM service providers segment had taken 47% market share in 2025.
Laboratory equipment services, 43.6% of the total laboratory services market in 2024 Laboratory equipment services dominate the overall laboratory services market, being capital-intensive because of the modern laboratory instrumentation, as well as the critical nature of equipment performance assurance in regulated and research laboratories worldwide.
The Laboratory Equipment Services Market Trends present significant growth opportunities due to several factors:
The unremitting worldwide growth of the demand for laboratory equipment services is the first structural force fueling the demand for the power of pharmaceutical research and development activity, fueled by the demographic of the aging population, the introduction of sophisticated biologic and advanced therapy medicinal products pipelines, the speeding up pace of precision medicine discovery, the post-pandemic revival of the interest in researching infectious diseases, and the intensive utilization of the sophisticated analytical tools that have been implemented in the pharmaceutical research and development setting necessitate the high standard of professionals to support the performance and compliance. IQVIA reported that in 2024, the global pharmaceutical R&D spending is USD 272 billion, a 6.8% rise compared to 2023, with investment in oncology, immunology, neurology, and rare disease therapeutic categories, which have the highest needs of analytical instrumentation, accounting for the majority of the spending.
The 21 CFR Part 11 regulation of the FDA regarding electronic records and electronic signatures in pharmaceutical laboratories, the EU regulation on the computerized system, GMP Annex 11, and ICH Q7 principles of active pharmaceutical ingredient manufacturing make up a comprehensive set of mandatory equipment qualification, calibration, and validation requirements that bring in recurring service revenue that is completely independent of equipment age or its operating condition. A survey conducted by PwC in 2024 of leaders of pharmaceutical quality operations reported that regulatory compliance-driven laboratory equipment servicing constituted 61% of the total laboratory service expenditure at large pharmaceutical companies, and the remaining 39% constituted performance optimization and operational efficiency-driven service activities. The growing number of 483 observations and warning letters issued by the FDA because of the inadequacies of laboratory equipment in calibration procedures and the inadequacies of laboratory controls included as one of the most commonly cited categories of violation of GMPs is further compelling pharmaceutical companies to consider awarding full-fledged service contracts that will supply them with full documentation of compliance and audit-ready records of calibration.
The total value of analytical and life science instruments installed within global laboratories has increased by enormous margins over the last 10 years due to the increasing activity in research, the growth in the volume of diagnostic testing, the growth in food safety testing, and the growing pressure on environmental monitoring, and is expected to continue growing to an estimated value in 2024 of USD 180 billion in installed capital equipment that delivers a high level of recurring service demand independent of the new instrument purchase activity. Modern analytical instruments, such as high-resolution mass spectrometers, next-generation DNA sequencing systems, automated liquid chromatography platforms, flow cytometers, and electron microscopes, are capital investments of USD 50,000 to USD 3 million+ per instrument and include electronic, optical, mechanical, and software components of unusual complexity beyond the scope of economic development in-house by laboratory end-users.
The cost of maintaining complex analytical equipment is about 8-18% of the original gear purchase price (depending on the type of service provided), indicating the worth of technical assistance, replaceable components, and compliance paperwork. For instruments like triple-quadrupole mass spectrometers, service contracts are USD 15,000-USD 80,000 per instrument annually. A 2024 SDi (Strategic Directions International) market intelligence survey found that 73% of laboratory managers in mid-to-large pharmaceutical and biotechnology companies claimed to have increased outsourcing of equipment maintenance and calibration to external service providers in the last two years and that the complexity of modern instruments, the difficulty of recruiting and retaining qualified service engineers, and the cost-effectiveness of specialized service providers compared to an in-house service team were the main drivers of the outsourcing trend. In 2024, the global laboratory outsourcing market is expected to reach USD 87.4 billion at a CAGR of 9.0 in 2032, equipment services are the most established category of laboratory outsourcing activity and the most contractually stable.
What are the Major Advances Changing the Laboratory Equipment Services Market Today?
The Internet of Things (IoT) sensor network, machine learning analytics, and cloud-based service management platform integration of laboratory instrument service delivery are radically changing the economics and efficiency of laboratory equipment maintenance - turning the industry away from a reactive break-fix service and time-based preventive maintenance to condition-based predictive maintenance where incipient equipment failures are detected and corrected before they lead to instrument downtime, data integrity breaches, and safety incidents. Embedded sensor arrays on modern laboratory measurement devices by major vendors such as Agilent Technologies, Waters Corporation, Thermo Fisher Scientific, and PerkinElmer are becoming more factory-equipped with close-out data streams that are processed by cloud-based analytics platforms to detect signs of deviation patterns that reflect a developing failure with ample lead time to undertake service responses. Waters Corporation has the CONNECT platform, Agilent has CrossLab Connect digital laboratory service infrastructure, and Thermo Fisher Scientific has Service Cloud as the most prominent commercial systems in this paradigm of IoT-predictive maintenance, these systems use tens of thousands of instruments connected to cloud analytics engines to process performance data in real time and issue automatic service warnings when instrument performance varies out of operational performance baselines.
Data provided by early adopters of the IoT-based predictive maintenance program implementation in the industry show that the experience of unplanned instrument downtime is decreased by 35-55% in comparison with traditional scheduled maintenance practices, and the average time of repair reaction is decreased from 48-8 hours (characteristic of the reactive break-fix service) to 4-8 hours of predictive intervention planned in advance. The economic impact of time saved by avoiding downtime in a pharmaceutical quality control laboratory setting - where instrument downtime directly postpones the decision to release batches and where the manufacturing cost impact of one day of production is USD 10,000-USD 500,000 - will create a strong business case to implement IoT-enabled service contracts despite the high premium subscription fee. MarketsandMarkets research indicates that the laboratory IoT market will increase to USD 16.2 billion in 2029 with a CAGR of 22.7%, with equipment condition monitoring being the most widely used use case in the portfolio of laboratory IoT applications.
The laboratory instrument calibration methodology modernization - the movement of periodic calibration point-in-time to continuous performance monitoring, the introduction of traceable NIST-traceable digital reference standards with uncertainty measurements, the creation of automated calibration execution facilities, and the integration of calibration data management with laboratory information management systems (LIMS) - is developing more valuable, defensible calibration service offerings that fetch premium prices and can develop long-lasting customer relationships than traditional manual calibration service offerings. Calibration services account for the greatest share of laboratory equipment services by revenue at about 32% of the total market share in terms of the non-negotiable and recurring nature of calibration needs of regulated laboratory settings - with ISO/IEC 17025-accredited calibration a mandatory requirement on any measurement that has any say in regulated decisions that fall under GxP, clinical diagnostic, or environmental regulatory frameworks.
The world calibration services market is currently estimated to be USD 7.2 billion in 2024 with pharmaceutical and life science calibration as the most valuable and fastest-growing category of the larger industrial calibration services market. Developed technologies such as automated multipoint calibration platforms, which actually perform full characterization of the performance of analytical instruments throughout their entire operating range in 248 hours or less as compared to 816 hours in the case of more traditional manual methods of calibration, digital calibration certificates with audit logs secured by blockchain, and mobile calibration laboratories deploying field-portable reference standards and calibration equipment to customer locations to perform in-situ calibration without the removal of analytical instruments are all adding to the value per calibration event and validate the dynamics of premium pricing dynamics that make calibration services the most financially attractive component of the laboratory equipment services market.
By Service Type
Why Does Calibration Services Lead the Market?
Calibration services will constitute the largest share of service types, with some 32% of the entire market space in 2025. Such a hegemony is indicative of the obligatory, repeated and non-deferrable character of instrument calibration requirements throughout regulated laboratory settings, where lawful and regulatory quality of measurement information, and thus the conformity of pharmaceutical batches, clinical diagnostic outcomes and food safety testing outcomes are conditional on provable currency of instrument calibration. Calibration frequency requirements depend on the type of instrument and regulatory regime: pharmaceutical GxP laboratories usually calibrate balances and pipettes in 3–6 months, HPLC systems in 6 months or more, temperature-controlled equipment in 3 months or more, and reference standards in 1 year or more, creating high-frequency recurring customer touchpoints that create a lasting customer relationship and predictable revenue streams of service providers.
The international laboratory calibration market serves an assumed 850 million calibration events per year of all types of instruments and industries, with the pharmaceutical and clinical sectors representing a subset of 42% of the total calibration expenditure they have a combination of a large instrument base, stringent regulatory requirements, and high calibration prices. The ISO/IEC 17025 accreditation, the international standard of the competence of testing and calibration laboratories is becoming an increasing requirement by regulatory agencies and pharmaceutical standards of quality as a requirement prior to calibration service providers serving GxP settings, establishing a substantial quality barrier of entry that is favorable to established, accredited calibration service organizations and is conducive to high-price dynamics. The calibration service market is also enjoying the gradual growth of measurement intensive applications such as continuous monitoring of bioprocesses, active environmental management in manufacturing plants, and automated testing analysis which is establishing new calibration needs in addition to the existing batch-testing laboratory equipment.
By Equipment Type
Why Do Analytical Instruments Lead the Market?
The largest equipment type segment is analytical instruments, with a market share of about 38% of the total market share in 2025 due to the exceptional breadth, sophistication, and capital value of the entire installed base of analytical instruments; the high technical complexity and precision demands of analytical instrumentation that requires special service skills, and the regulatory importance of the performance of analytical instruments in the pharmaceutical quality control, clinical diagnostics, food safety testing, and environmental measurements applications where the performance of the measurement by a specific instrument directly determines the compliance result. There is currently an estimated USD 56.8 billion global market in API analytical instruments, estimated to grow to USD 94.2 billion in 2030, with the service revenue of this installed base estimated at 12-15% of instrument capital value between key major categories of analytical instruments each year. High-performance liquid chromatography (HPLC) systems - one of the most widely deployed analytical systems in the world, with an estimated number of installed systems of more than 500,000 in pharmaceutical and research laboratories - produce large amounts of service revenue each year in terms of pump seal replacement, detector lamp replacement, column oven maintenance, software qualification, and system suitability verification services. The most service-intensive category of analytical technique at present is mass spectrometry, which is experiencing a boom of triple-quadrupole, Orbitrap and time-of-flight instrumentation that has become ubiquitous in pharmaceutical, clinical and food safety labs with service outages valued at USD 5,000-USD 25,000 per event at major pharmaceutical and contract testing laboratory clients.
By End-User
Why Do Pharmaceutical & Biotechnology Companies Dominate?
The largest end-user segment with an approximate market share of 34% in 2025 is the pharmaceutical and biotechnology industry, due to the combination of the highest density of laboratory instruments per laboratory facility in the world, the most rigorous requirements for regulatory compliance of equipment operation and reporting in any industry sector, the greatest concentration of high-end analytical instrumentation that must call on specialized service expertise, and the most established laboratory equipment service contract programs of any business. A typical large pharmaceutical manufacturing facility has 500-2000 calibrated devices in the quality control and analytical development as well as process development and environmental monitoring units with USD 3-12 million annually in laboratory equipment service costs depending on the size of the site and complexity of the instrument fleet. The GMP compliance model of the pharmaceutical industry provides a scenario that is unique in all the laboratory service customer segments, services cannot be delayed due to cost considerations without creating regulatory compliance risk, resulting in inelasticity of demand, which facilitates premium service pricing and supports service revenue during cost reduction programs of pharmaceutical companies. The global pharmaceutical manufacturing market is estimated to be USD 561 billion in 2024 and is expected to grow to USD 868 billion by 2030, which will continue to support the growth of the pharmaceutical laboratory equipment installed base to drive the growth of the laboratory service market.
By Service Provider
Why Do OEM Service Providers Lead the Market?
OEM service providers represent the biggest segment of service providers with around a 47% market share in 2025, which is a result of the knowledge of proprietary advantage possessed by OEMs over their own instrument architecture, such as access to proprietary diagnostic codes, first call to engineering notice and software updates, special availability of certain spare parts, and the unspoken privilege of manufacturer-approved service quality that is still pertinent to regulated laboratory customers with mandated vendor qualification. The OEM service companies of large instrument manufacturers such as Thermo Fisher Scientific, Agilent Technologies, Waters Corporation, and Mettler-Toledo have geographic coverage and technical depth for complex repair events through thousands of factory-trained field service engineers that cannot be easily replicated by ISOs without the same investment in training. But OEM service market share has been steadily decreasing, from an approximation of 58% in 2018 down to 47% in 2025 as ISO capabilities grow; price differences between OEM and ISO service contracts are generally 20-35% lower between similar ISO multi-vendor contracts and OEM single-vendor contracts based on an analysis of laboratory procurements; and ISO organization investment in training, parts, and quality management infrastructure enhances manager satisfaction with ISO service quality.
Report Scope
Feature of the Report | Details |
Market Size in 2026 | USD 31.47 billion |
Projected Market Size in 2035 | USD 62.83 billion |
Market Size in 2025 | USD 28.94 billion |
CAGR Growth Rate | 8% CAGR |
Base Year | 2025 |
Forecast Period | 2026-2035 |
Key Segment | By Service Type, Equipment Type, End-User, Service Provider and Region |
Report Coverage | Revenue Estimation and Forecast, Company Profile, Competitive Landscape, Growth Factors and Recent Trends |
Regional Scope | North America, Europe, Asia Pacific, Middle East & Africa, and South & Central America |
Buying Options | Request tailored purchasing options to fulfil your requirements for research. |
How Big is the North America Market Size?
The North America laboratory equipment services market size is estimated at USD 11.29 billion in 2025 and is projected to reach approximately USD 23.46 billion by 2035, with a CAGR of 7.6% from 2026 to 2035.

Why Did North America Dominate the Market in 2025?
As the largest pharmaceutical and biotechnology R&D market globally, hosting the FDA, the world's regulatory gold standard whose laboratory equipment compliance requirements define industry practice, the greatest concentration of major research universities and academic Medical Centres and state research laboratories with the most advanced analytical instrumentation fleet, and the commercially most mature laboratory equipment service market with the highest concentration of OEM, ISO and specialist calibration service providers seeking customer relationships in the world, North America controls in the 2025 market about 39% of total world market share. In the United States, the pharmaceutical and biotechnology sector made a USD 117 billion investment in domestic research and development in 2024 courtesy of PhRMA and has supported the largest pharmaceutical laboratory equipment installed base in the world and a corresponding laboratory equipment services demand.
The U.S. clinical diagnostics market, including hospital laboratories, reference laboratories, and physician office laboratory environments, conducts some 14 billion laboratory tests annually, according to the American Clinical Laboratory Association, which is a large installed base of clinical analyzers, point-of-care instruments, and laboratory automation systems, which need broad-based service and maintenance support. With a USD 47.8 billion annual budget, of which about 85% goes to extramural research at universities, medical schools, and independent research centers, the NIH maintains a rich and instrument-intensive academic research laboratory sector, creating a high demand in the equipment service market in all major instrument categories.
U.S. Market Trends
The market in the U.S. is described by multi-vendor ISO service contract maturation as a contracting service model of choice among large-scale pharmaceutical and hospital laboratory networks, the increasing popularity of IoT-enabled predictive maintenance service platforms among the major pharmaceutical manufacturers aiming to minimize service cost and laboratory down-time at the same time, the increasing complexity and capital intensity of next-generation analytical instruments yielding higher per-instrument service revenue, and the continuing regulatory focus by the FDA on compliance with equipment use by laboratory networks that creates continuous compliance-driven service demand regardless of the overall The increasing influence of Contract Research Organizations (CROs) as significant clients of laboratory equipment service providers is also a characteristic feature of the U.S. market, as CROs with high-throughput test operations need the services of the top-quality equipment contractor with guaranteed responsiveness and availability of the equipment commitment to client schedules commitments that are valuable in the context of the studies.
Why is Europe a Strategically Critical Market?
The second-largest regional market is Europe, which is supported by the second-largest pharmaceutical manufacturing and R&D center in the world, based in Germany, Switzerland, the United Kingdom, France, and Ireland, a highly developed network of national metrology institutes, including the PTB in Germany, the NPL in the United Kingdom and France, and other countries that provide national calibration traceability infrastructures and accreditation systems governing the quality of laboratory calibration services, and an advanced hospital and clinical laboratory industry, which performs an estimated 8 billion diagnostic tests each year in Germany. Germany is the biggest national market in Europe in terms of laboratory equipment services, with the country-based pharmaceutical and chemical sector, which consists of BASF, Bayer, Merck KGaA, and Boehringer Ingelheim, as well as the outstanding concentration of academic research Universities and Fraunhofer Institutes that keep elaborate analytical laboratory frameworks. The UK has a large pharmaceutical sector, such as AstraZeneca, GSK, and the Wellcome Sanger Institute, and due to the presence of the National Health Service, it is the second largest European market in terms of national laboratory equipment services, and the compliance with EU GMP recognition of its certification of compliance is creating further regulatory challenges around its recognition of compliance that is driving the demand for qualification and validation services in sites used by pharmaceutical companies operating under both EMA and MHRA compliance systems.
Why is Asia Pacific the Fastest-Growing Regional Market?
The fastest-growing regional market with a forecasted CAGR of 10.4% between 2026 and 2035 is the Asia Pacific, which has explosive growth in the pharmaceutical manufacturing and R&D investment of China, India, South Korea, and Japan and is subject to the ever-growing clinical laboratory infrastructure serving the 4.7 billion population of the Asia Pacific with its rapidly modernizing health care systems, the maturation of Asian pharmaceutical regulatory frameworks, the NMPA reforms in China that are being updated in line with ICH guidelines. The pharmaceutical sector of China, which is estimated to be USD 185 billion in 2024 with a 6.8% CAGR, is in the process of a fundamental quality shift due to the comprehensive drug regulatory reform program conducted by NMPA, where domestic pharmaceutical manufacturers are heavily investing in upgrades of analytical instruments and laboratory equipment qualification programs to comply with new GxP standards needed to gain approval to operate on the domestic market and also enter the target market. The pharmaceutical sector of India, the third largest by volume in the world and the largest provider of generic drugs in the world, is also making investments in the modernization of laboratory infrastructure to adjust to the FDA's heightened inspection of Indian pharmaceutical manufacturers, and the demand for laboratory equipment calibration and qualification services is increasing at an approximate 14.2% CAGR in India alone.
China Market Trends
It is projected that the laboratory equipment services market in China is approximated to be USD 2.84 billion by the year 2025 and is expected to grow at the rate of 12.1% in the coming decade due to the increasing number of domestic pharmaceutical companies operating in China that require laboratory equipment services qualification by GMP and the growing volume of multinational pharmaceutical firms that need the services of GMP compliant laboratory equipment in China. The high level of investment of China in scientific research is maintaining the high growth of the academic and government research laboratory equipment installed base which produces increasing laboratory equipment service demand: R&D spending is estimated by the National Bureau of Statistics to be USD 452 billion in 2023, or 2.64% of GDP. The domestic Chinese providers of laboratory equipment services such as Sinolab, the Calibration Center of the China National Institute of Metrology and local ISO operators are building services to compete with the subsidiaries of international service providers such as the China Service operations of Thermo Fisher Scientific, the CrossLab China division of Agilent and the Asia Pacific service organization of Waters Corporation.
Why is the Middle East & Africa Region an Emerging Growth Market?
The LAMEA region is showing increasing market development due to Saudi Arabia and UAE Vision 2030 and Vision 2071 healthcare and industrial development programs that include extensive investment in laboratory modernization of hospitals, development of pharmaceutical manufacturing, and food safety testing facilities; the world-leading biotechnology research sector in Israel based on the Weizmann Institute and Hebrew University that creates the demand for advanced laboratory instrument services by academic and biotechnology company laboratories; the large pharmaceutical manufacturing sector in Brazil - with domestic pharma revenue of over USD 28 billion in 2024 — generating GMP-compliant laboratory service requirements; and South Africa's academic and public health laboratory sector supported by the Africa Centres for Disease Control and Prevention (Africa CDC) investment in diagnostic laboratory infrastructure across sub-Saharan Africa representing an emerging growth frontier for laboratory equipment service organizations.
The market has experienced large developments as companies in the industry attempt to execute larger digital service offerings, augment multi-vendor service offerings, and win upon increased demand by regulated pharmaceutical and clinical lab end-users globally.
In February 2026: Agilent Technologies stated that it was expanding its CrossLab Connect IoT-based lab service platform to accommodate another 45 non-Agilent OEM instruments.
In January 2026: Thermo Fisher Scientific declared the availability of its Unity Lab Services Digital Validation Suite, a cloud platform that automates the execution of IQ/OQ/PQ protocols, real-time data movement through instrument interfaces, conformance evaluation, electronic generation of reports, and integration with the LIMS, to regulated pharmaceutical laboratory clients in January 2025.
These strategic initiatives have enabled the firms to consolidate market position, enhance digital services technology, and increase geographic reach in the buoyant pharmaceutical markets, as well as leverage the large and rising demand base manifested by fleet expansion of laboratory equipment, intensifying regulatory compliance, and the progressive outsourcing of laboratory equipment service by the specialized service providers in the pharmaceutical, clinical, and industrial end-user markets of laboratory equipment worldwide.