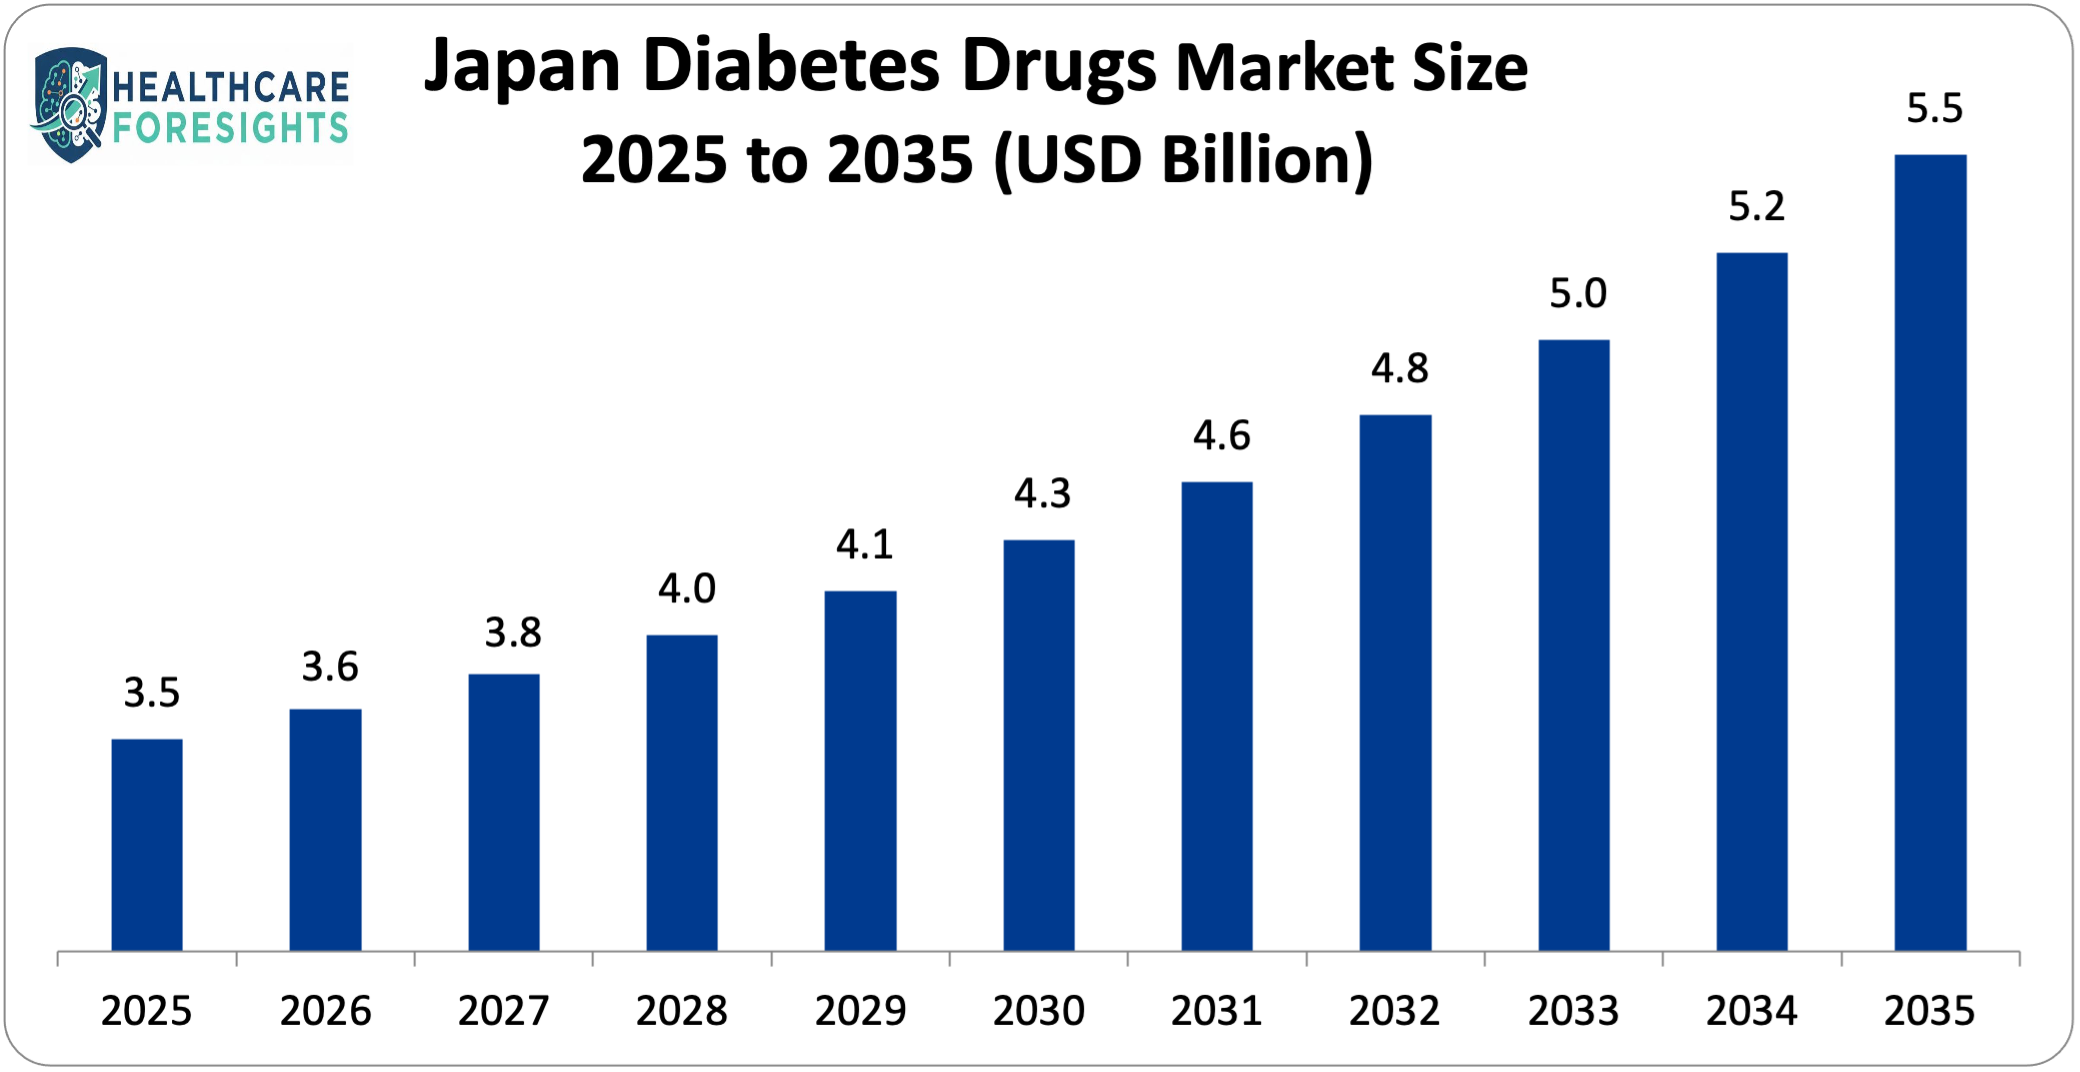
The market size of the Japan diabetes drugs market is estimated to be USD 3.5 billion in 2025, and it is estimated that such a market size will rise to USD 3.6 billion in 2026, and to around USD 5.5 billion in 2035, at an annual CAGR of 4.6% between the years 2026 and 2035 with the increasing prevalence of diabetes, ageing population and the increasing use of novel therapies. The maintenance of the market is likely to grow beyond 2035 due to the continuous development of drugs and adequate healthcare infrastructure.
DPP-4 inhibitors accounted for approximately 35.3% of total market revenue in 2025
SGLT-2 inhibitors segment are expected to register the highest CAGR of 5.2% from 2026 to 2035
Type 2 diabetes represented nearly 63.5% of total drug demand in 2025
Oral antidiabetic drugs contributed around 65.5% of total market consumption in 2025
Retail pharmacies accounted for approximately 46.5% of total distribution share in 2025
The Japan diabetes drugs market Trends present significant growth opportunities due to several factors:
Increasing Diabetes Prevalence and Aging Population: The aging society of Japan is a significant growth driver in the diabetes drugs market, given that the prevalence of diabetes is high with advancing age. The elderly populations are characterized by increased levels of both impaired glucose tolerance and type 2 diabetes, leading to increased demand for long-term treatment and chronic use of therapy. The population trend increases the level of patient groups that demand long-term pharmacological care, leading to greater interest in the use of drugs and portfolios of diversified therapeutic options in insulin and new oral agents. The increasing number of geriatric populations is also a reinforcement to the healthcare policy of diabetes management programs with a focus on the benefit of prescribing and reimbursement of diabetes medications specific to geriatric patients. Diabetes prevalence in adults (approximately 8.1% or 9 million out of 113.7 million) also shows large treatment burdens in the long term in Japan in 2024.
Type 2 Diabetes and Lifestyle Risk Factor: Type 2 diabetes nowadays is increasing in incidence due to lifestyle changes that have altered the lifestyles of Japanese people; the lack of physical activity, western patterns of eating, and the rising rate of obesity have all increased the number of patients with type 2 diabetes, who need to be medicated. Community studies have reported substantial age-distributed trends in the prevalence of type 2 diabetes in adults in the past decades, especially among older age groups as part of larger changes in health risk factors. Since type 2 diabetes constitutes the largest proportion of cases, oral medications, combination therapies, and injectable agents increase in long-term usage. This tendency promotes the development of a variety of drug classes and the necessity of complex treatment. During the period 1988 to 2002, the prevalence of age-adjusted type 2 diabetes increased significantly among the Japanese adults.
Government Healthcare Expenditure and Chronic Disease Focus: The universal healthcare insurance system in Japan and a high amount of healthcare expenditure confirm the focus on chronic disease management of Japan, including diabetes. The government policy systems focus on broadening the takeaway of the diagnostics, the successful therapy compliance, and the reimbursement of the medication, which promotes the usage of the diabetes medications by all categories of patients. Routine screening interventions and care pathways with subsidies decrease the barriers to the initiation and continuation of pharmacotherapy to enhance long-term health outcomes and patient adherence to the drug regimens. Besides, market expansion is helped by awareness campaigns and clinical guidelines, which increase systematic pharmacological intervention in diabetes treatment. In Japan, the total expenditure on healthcare was about ¥43 trillion (~USD 304 billion), which is an indication of high support of the service to treat chronic diseases.
Diversification of Therapeutic Options: The Japanese and Thai markets of diabetes drugs has the advantage of a diversified therapeutic environment that incorporates contemporary therapeutic agents like GLP-1 receptor, DPP-4 inhibitors, and SGLT-2 inhibitors. These new classes of drugs provide better glycemic regulation, cardiovascular advantages, and patient adherence benefits in comparison to conventional treatments, which blatantly increases their clinical use. They have increased prescription trends and promoted individualized treatment programs, particularly in patients with comorbid conditions such as cardiovascular disease or chronic kidney disease. This therapeutic diversification improves clinical outcomes and leads to an increase in medication use in all categories of patients, which is a beneficial step in improving the overall growth of the market as clinicians switch to the evidence-based advanced treatments. New classes of drugs are gaining an increasing complement to the old insulin and oral regimens.
Greater Attention to Long-term Disease Management : Clinical attention to long-term glycemic control is becoming increasingly common in preventing diabetes complications (cardiovascular, renal, nerve, and neurological consequences). The concern influences continuous pressure on long-term pharmacotherapy, frequent medicine modifications, and combinations to maximize control of the disease. The clinical practice guidelines promote the use of early evidence-based therapies, ongoing therapy monitoring, and prevention-based treatment plans, which further boost the use of drugs. Since patients are constantly under medicine regimes, they are taking medications all their lives, which enhances consumer demand. Japan has a long history of focusing on systematic chronic disease care, which leads to medication retention among patient groups over time, which strengthens the regularity of taking medicine.
What are the Major Advances Changing the Japan diabetes drugs market Today?
Strict Drug Pricing Regulations and Pricing Policies: Japan has a tough system of control over the price of drugs; the Ministry of health, Labour and Welfare, and the National Health Insurance (NHI) system restrict the price elasticity and profitability of diabetes drugs. Government policies require a biannual review of price and possible reduction of prices according to the market pricing and volume trends, putting pressure on the revenues downwards. On the one hand, these controls are beneficial to patients, but they limit the pricing policies of manufacturers and may decrease the motivation to introduce new drugs. Besides, cost-effective criteria of reimbursement ensure that premium pricing is hard, particularly when it comes to new agents that lack clinical data with substantial advantages. Japan, via a systemic review of drug prices, constantly decreases reimbursement rates of established products, which is biannual.
Regulatory Lags in the Approval of new drugs: The Pharmaceuticals and Medical Devices Agency (PMDA) has very tough clinical conditions to pass to approve new diabetes drugs, which frequently leads to longer review periods than in some other markets. These procedures are safe and effective yet slow down entry of new therapies to the market and restrict early adoption and competitive benefits. A small and mid-sized developers, in particular, might encounter difficulties in making their way through the Japanese regulatory environment and slow down the process of introducing new classes of drugs. Slow approvals delay revenue realization and may be counterproductive to the dynamism in the market in general, where therapies developed outside Japan are already in the international markets. The Japanese regulatory review process of new diabetes drugs can take more than 20 months.
Competitive Pressure: Branded diabetes drug sales are subject to competitive pressure posed by the emerging use of generic drugs under the national Health Insurance and cost-reduction programs of Japan. The incentives provided by the government favor the generic substitutes to bring down insurance spending, leading to a high level of price erosion and low margins to the original products. The manufacturers of branded diabetes therapies have a problem with the market share and price restriction, especially on the long-listed products whose exclusivity has lapsed. This move impedes the increase in revenue and increases competition. The governmental policies of Japan promote the use of generics and even lower the prices of drugs by about 20 percent.
By Drug Class
Why DPP-4 Inhibitors Dominate the U.S. Diabetes drugs Market?
DPP-4 inhibitors control the Japanese diabetes drugs market because they are highly acceptable clinically, have a positive safety profile, and are appropriate to the Japanese patient population. These medications are also effective in controlling blood glucose at minimal risk of developing hypoglycemia and weight gain and are therefore suitable to patients in old age, who constitute a big proportion of diabetic patients in Japan. The DPP-4 inhibitors have historically been prioritized in Japanese treatment guidelines as an early-line treatment of Type 2 diabetes. Large physician familiarity, long-term real-world experience, and high reimbursement coverage also enhance the widespread adoption. Moreover, robust local innovation and co-marketing deals have seen comprehensive access to branded and generic DPP-4 inhibitors, and this has enhanced their dominance in prescriptions.
Why SGLT-2 Inhibitors and GLP-1 Receptor Agonists Is the Fastest-Growing Product Segment?
The most rapidly expanding classes of drugs in Japan are SGLT-2 inhibitors and GLP-1 receptor agonists because they have cardiovascular, renal, and weight-loss advantages. The growing clinical evidence of the need for them in lowering the risk of heart failure and chronic kidney diseases has changed the prescription patterns to favor them. Japanese doctors are also leaning towards more outcome-based management methods as opposed to glucose control. The growing influence of obesity, particularly in middle-aged adults, has also led to the surge in the need for GLP-1-based treatment. Continued label expansions, better injectors, and oral GLP-1 preparations are further contributing to uptake growth, making these classes of drugs some of the major drivers of growth.
By Diabetes Type
Why Type 2 Leads the Market?
The highest market share of the market of diabetes drugs in Japan is attributed to Type 2 diabetes, which has a high prevalence level, persistent nature, and prolonged duration of treatment. The change of lifestyle, the aging population, and nutrition have greatly contributed to the incidence of Type 2 diabetes in Japan. Patients are generally on long-term pharmacological therapy with or without a number of different classes of drugs throughout their lives, which promotes long-term use of drugs. Screening programs and early diagnosis programs led by the government have increased the number of people to be treated. Also, intensive therapy and combination drug use commonly among Type 2 patients lead to prescription volumes, which can be considered a leading contributor to revenue.
Why Gestational Diabetes Is the Fastest-Growing Application?
The observed maternal age and pregnancy-related metabolic risk factors, which are on the increase in Japan, have made gestational diabetes the fastest-growing diabetes type segment. Better prenatal screening guidelines and increased awareness of the obstetricians have contributed to increased rates of diagnosis. Although the length of treatment is shorter, the growing use of insulin and glucose-lowering drugs during pregnancy is increasing the growth of the market. This focus on maternal and neonatal results in the field of public health has enhanced the priority to provide early intervention, which is essential in promoting its rapid growth as opposed to Type 1 and Type 2 segments.
By Route of Administration
Why Oral Drugs Dominate Route of Administration?
The Japan diabetes drugs market is controlled by oral antidiabetic drugs because the patients like them, they may be taken easily, and the adherence rates are high. Being a nation with a deep history of oral medication use, Japan is heavily dependent on oral therapies, including DPP-4, SGLT-2, and biguanides. Drugs taken by mouth lessen the injection burden, especially in the elderly population, where oral medications fit well into the outpatient care paradigm. Large coverage of reimbursement and the presence of once-daily preparations further increase patient compliance. These benefits render oral medication the most common method of administration in Japan.
Why Injectable Therapies Are the Fastest-Growing End Users?
Fastest-growing route comprises injectable therapies as the usage of GLP-1 receptor agonists and improved insulin formulations increases. Such innovations as prefilled pens, the weekly dosing procedure, and better safety profiles reduce the barriers associated with injections. The growing emphasis on aggressive glycemic regulation and weight loss is driving faster acceptance of injectable therapy, especially in complicated Type 2 diabetes patients.
By Distribution Channel
Why Retail Pharmacies Dominate Distribution?
The distribution of diabetes drugs in Japan is dominated by retail pharmacies to the extent that there is a strong outpatient treatment model and the existence of pharmacy networks. A majority of diabetes patients have their prescriptions filled out in the local pharmacies, thus having access to and continuity of care for medications. The universal healthcare segment of Japan encourages high rates of prescription refills, which strengthens the market control of retail pharmacies. Pharmacist-led counseling enhances compliance, which enhances this channel.
Why Online Pharmacies Are the Fastest-Growing?
Online pharmacies have the highest growth rate because of the rising use of digital health care and the demand for convenience. Expansion in e-prescriptions, home delivery, and chronic disease management platforms is increasing online access, especially for urban and working patients.
By Patient Type
Why Adult Patients Dominate the Market?
The Japan diabetes drugs market comprises the highest proportion of adult patients since the middle-aged groups are the most susceptible to diabetes. The main reasons that cause permanent drug demand among this group are high workforce stress, sedentary lifestyle, and diet. Even in adult patients, intensification of therapy is more increased, which stimulates the prescriptions.
Why Geriatric Patients Are the Fastest-Growing?
The geriatric population is the quickest expanding demographic, since there is a rapidly aging population in Japan. Increased disease management and longer life expectancy have led to an expansion in the duration of treatment, resulting in the need to find safer and well-tolerated diabetes treatments that cater to the specific needs of the elderly.
Report Scope
Feature of the Report | Details |
Market Size in 2026 | USD 3.6 billion |
Projected Market Size in 2035 | USD 5.5 billion |
Market Size in 2025 | USD 3.5 billion |
CAGR Growth Rate | 4.6% CAGR |
Base Year | 2025 |
Forecast Period | 2026-2035 |
Key Segment | By Drug Class, Diabetes Type, Route of Administration, Distribution Channel, Patient Type and Region |
Report Coverage | Revenue Estimation and Forecast, Company Profile, Competitive Landscape, Growth Factors and Recent Trends |
Buying Options | Request tailored purchasing options to fulfil your requirements for research. |
The market has undergone significant developments as industry participants seek to expand capabilities and enhance product portfolios.
In March 2023, Health2Sync also announced an update of their Health2Sync App with insulin data integration with the Mallya Cap insulin cartridge, a biocorp-developed insulin cartridge commercially introduced in Japan by Novo Nordisk. This boosts digital diabetes management, as it allows tracking insulin more accurately and monitoring the patient.
In September 2022, the Ministry of Health, Labour, and Welfare of Japan authorized Eli Lilly's diabetes drug Mounjaro (tirzepatide). Distribution and commercialization of Mounjaro in Japan are to be done by Mitsubishi Tanabe Pharma Corporation, which has signed a sales collaboration agreement with Celmark in July 2022.
These strategic activities have allowed companies to strengthen market positions, expand product offerings, enhance technological capabilities, and capitalize on growth opportunities within the expanding market.